



Semicon 2.0: India’s Rs 1.27 lakh crore Semicon 2.0 push has put four very different listed businesses in the same conversation: CG Power, Kaynes Technology, Dixon Technologies and Tata Elxsi. But there is already a sizeable difference in where the four stand. CG Power has begun commercial production at its OSAT plant. Kaynes is building out OSAT and PCB manufacturing. Dixon is moving deeper into components, while Tata Elxsi is taking the semiconductor route through engineering and design services.
CG Power and Industrial Solutions Ltd. has already moved from project development to its first commercial shipment. Kaynes is spending heavily to bring its semiconductor and PCB businesses into production. Dixon Technologies is adding manufacturing depth around displays, cameras and other components. Tata Elxsi is building its semiconductor presence through engineering, embedded technology and product development.
Semicon 2.0: 4 companies, 4 different focus
The government’s August 31 notification gives the buildout a much larger policy backdrop. Semicon 2.0 covers chip design, semiconductor equipment and materials, fabrication, ATMP and OSAT, R&D and talent development. The four companies have exposure to different parts of that chain, with CG Power and Kaynes focused on semiconductor manufacturing, Dixon moving deeper into components and Tata Elxsi building engineering capabilities.
One company is already shipping packaged semiconductors. Another is preparing new semiconductor and PCB capacity for commercial operations. Dixon is pushing deeper into components, while Tata Elxsi is building around engineering and technology services. The pace at which these businesses turn those capabilities into commercial opportunities will determine how their semiconductor stories develop.
Semicon 2.0 takes India’s chip push beyond fabs
The government’s Rs 1,27,500 crore Semicon 2.0 programme covers six pillars across the semiconductor value chain, including chip design, semiconductor equipment and materials, fabrication, ATMP and OSAT, R&D and talent development.
The incentives vary by activity. Silicon wafer fabs can receive support of up to 40% of eligible project cost, while advanced packaging under ATMP and OSAT can receive 35% support. Legacy packaging can receive 25%, while semiconductor equipment and materials projects can receive 30% capex support.
For CG Power and Kaynes, packaging and testing is the direct manufacturing link. Dixon’s opportunity comes through components and localisation around electronics manufacturing. Tata Elxsi sits further upstream, with engineering and embedded technology capabilities.
| Semicon 2.0 area | Government support / focus | Companies in focus |
| Chip design | Design incentives | Tata Elxsi |
| Equipment and materials | 30% capex support; equipment PLI | Kaynes, Dixon and wider ecosystem |
| Silicon semiconductor fabs | Up to 40% eligible capex support | No directly disclosed fab among the four |
| ATMP / OSAT | 35% advanced packaging; 25% legacy packaging | CG Power, Kaynes |
| R&D | Project support | Tata Elxsi and wider engineering ecosystem |
| Talent | Semiconductor skill development | All four through their respective businesses |
Source: Government of India, Semicon 2.0 notification and company disclosures.
CG Power: Commercial OSAT production puts its semiconductor business into operation
CG Power has crossed an important manufacturing milestone with CG Semi beginning commercial production at its G1 OSAT facility in Sanand, Gujarat.
The G1 facility has a peak capacity of 300 million units per year. It has completed equipment installation, process stabilisation, workforce training, customer qualification, and quality readiness.
CG Semi is a joint venture between CG Power, Renesas Electronics Corporation and Stars Microelectronics. The partners are investing more than Rs 7,600 crore over five years across G1 and G2. The second facility is under development.
The Sanand operation provides assembly and testing across traditional and advanced packages. It is positioned to serve automotive, defence, infrastructure, industrial and IoT applications.
Vellayan Subbiah, Chairman, CG Power, said during the commercial production launch, “Today, this first shipment speaks louder than any words. It reflects the enormous belief behind these small chips and the combined effort of a remarkable team.”
CG Power is building the semiconductor operation alongside its established electrical equipment business. The company said its semiconductor businesses reduced consolidated margin by Rs 43 crore, or 132 basis points, as it continued investing in the semiconductor talent pool.
The wider business had standalone Q1 FY27 order intake of Rs 4,692 crore, while the unexecuted order backlog stood at Rs 17,333 crore.
The immediate task is to build volumes at G1. G2 remains the next major capacity addition.
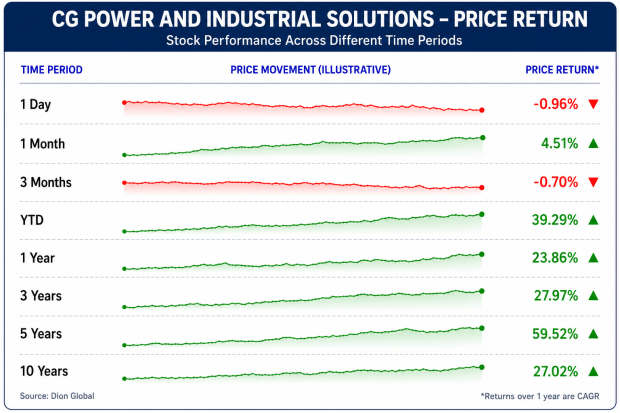
CG Power share price performance
Kaynes Technology: OSAT and PCB expansion moves towards commercial revenue
Kaynes is building its semiconductor presence through Kaynes Semicon, while its PCB operation adds another manufacturing layer.
The company spent Rs 473 crore on OSAT and Rs 324 crore on PCB in FY26. It also received Rs 170 crore in government subsidy for the OSAT business through July 2026.
Kaynes Semicon Unit 2 and Kaynes Circuit Chennai were targeted for operations in Q3 FY27. Management said the projects remained on track despite equipment and logistics-related delays.
During the earnings call, N. Muthukumar, Managing Director, Kaynes Technology India, said, “Our commitments, as indicated by the Executive Vice Chairman last year, are that we are going to have commercial revenue booking from this year, from the third quarter and fourth quarter, and we are committed to that. And the project is on track.”
Kaynes has also partnered with Mitsui through Kaynes Semicon. Management said the partnership is a major milestone for the subsidiary.
The PCB business has attracted interest from global customers. Management said PCB supply has tightened, with lead times reaching 6-8 months in some cases. Trials were underway with a global customer that had requested the company’s planned capacity.
The company also disclosed an engagement with one of the world’s largest EV manufacturers following a plant visit and positive feedback.
Kaynes’ Q1 FY27 revenue stood at Rs 946 crore, while its order book was around Rs 9,000 crore.
The next milestones are commercial production, customer qualification and revenue contribution from the new OSAT and PCB facilities.
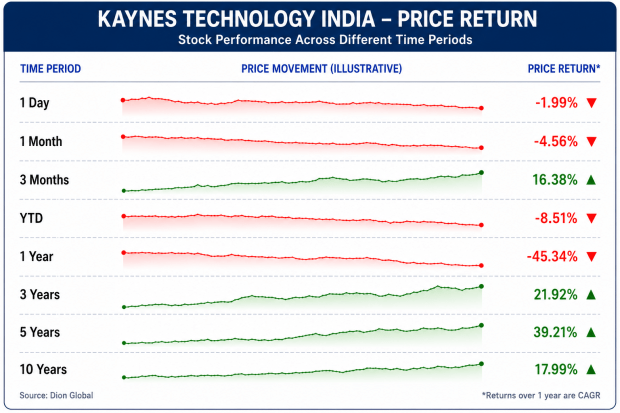
Kaynes Technology share price performance
Dixon Technologies: Components take its semiconductor exposure deeper into localisation
Dixon’s semiconductor exposure comes through components, localisation and backward integration rather than an OSAT facility.
Its two prominent component businesses are display modules and camera modules. Dixon has a joint venture with HKC for displays and another with Q Tech for camera modules.
During the earnings call, Atul Lall, Vice Chairman and Managing Director, Dixon Technologies, said, “So there are two parts of PLI 2. One part is going to be linked to your production value, which we feel largely will come from the global markets. The second is linked to the localisation, in which we understand the details are still awaited; they are mentioning five components, out of which we have a play in two, camera modules and display.”
Dixon is also working to build the capabilities behind those components. Lall said, “When you’re talking about display, I’m talking about materials. I’m talking about chemistry. When I’m talking about tools and dyes, I’m talking about deep metals, again, chemistry.”
The company is pursuing precision engineering as another part of this manufacturing expansion. Lall said, “So, please be rest assured, sir. We are aggressively working in that direction. Specifically in the area of precision engineering.”
Dixon has also installed an SSD line for its IT hardware business. Its Inventec joint venture is being developed around PCB assemblies and potential server manufacturing.
The company’s adjusted Q1 FY27 revenue was Rs 15,557 crore, while adjusted EBITDA stood at Rs 472 crore and adjusted PAT at Rs 218 crore.
The component strategy gives Dixon a route to capture more domestic manufacturing value as electronics production becomes increasingly localised.
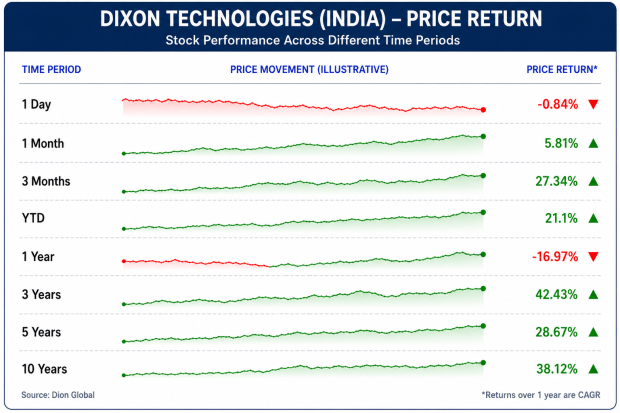
Dixon Technologies share price performance
Tata Elxsi: The listed Tata name with a semiconductor engineering link
Tata Elxsi’s semiconductor exposure sits on the engineering side, but the Tata group’s semiconductor manufacturing plans make the connection more relevant. Tata Electronics is building India’s first silicon wafer fab with PSMC, while Tata Elxsi operates in design and technology services, including electronics and embedded engineering. The two should not be treated as the same business, but Tata Elxsi gives the listed Tata group a technology-services presence alongside Tata Electronics’ manufacturing projects.
The Tata Electronics-PSMC project involves an investment of Rs 91,000 crore, with planned capacity of 50,000 wafers per month and manufacturing at 28nm to 110nm nodes for automotive, computing, AI and communications applications. Tata Electronics is the 100% equity owner of the project.
Tata Electronics has also entered into semiconductor partnerships that include Renesas, adding another connection between the Tata group’s manufacturing plans and global chip companies. The semiconductor material supplied for the story identifies Tata Electronics separately from Tata Elxsi, so the two businesses should not be presented as having the same ownership or revenue exposure.
For Tata Elxsi, the opportunity comes through engineering. Its services include research and strategy, electronics and mechanical design, software development, validation and deployment. The company works across transportation, media and communications, healthcare and medical devices.
The company reported Rs 1,021.1 crore of operating revenue in Q1 FY27. Revenue grew 6.5% YoY and 1.3% QoQ in constant-currency terms.
During the Q1 FY27 earnings conference call, Manoj Raghavan, Managing Director and Chief Executive Officer, Tata Elxsi, said, “These investments definitely are around building a specialised talent pool, that is definitely there. We talked about the AI infrastructure that is needed that we are building. So and also all the tools and the cloud investments that are needed to deliver value to our customers.”
Nitin Pai, Chief Marketing and Chief Strategy Officer, Tata Elxsi, also said during the call that the company’s proposition is based on leading-edge technology capabilities and deep domain expertise, with its own platforms being used to transform customer products and services and accelerate software development.
That puts Tata Elxsi in a different position from CG Power and Kaynes. Tata Electronics is the Tata group’s direct semiconductor manufacturing vehicle, while Tata Elxsi’s listed-market exposure comes through engineering and technology services.
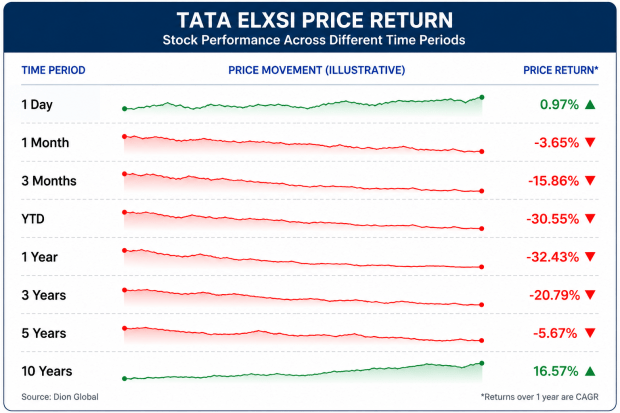
Tata Elxsi share price performance
CG Power, Kaynes, Dixon and Tata Elxsi: financial comparison
| Q1 performance | CG Power | Kaynes Technology | Dixon Technologies | Tata Elxsi |
| Q1 FY27 revenue | Rs 3,281 crore | Rs 946 crore | Rs 15,557 crore | Rs 1,021.1 crore |
| YoY revenue growth | 14% | 40% | 21% | 14.5% |
| Q1 FY27 EBITDA | Rs 481 crore | Rs 147.6 crore | Rs 472 crore | Rs 216 crore |
| EBITDA margin | 14.7% | 15.6% | 3.0% | — |
| Q1 FY27 PAT | Rs 308 crore | Rs 56.4 crore | Rs 218 crore | Rs 170.6 crore |
| ROCE | 20% | — | 34.1% | — |
| ROE | — | — | 23.4% | — |
| Order book / backlog | Rs 17,333 crore | ~Rs 9,000 crore | — | — |
Sources: Company Q1 FY27 filings, investor presentations and earnings-call material.
The valuation spread is wide. CG Power has the highest PE and EV/EBITDA in the comparison, while Tata Elxsi has the lowest on both measures.
Kaynes sits between CG Power and Dixon on EV/EBITDA. Dixon’s PE is below both CG Power and Kaynes, while Tata Elxsi has the highest dividend yield among the four.
What to watch in CG Power, Kaynes, Dixon and Tata Elxsi
For CG Power, G1 production volumes and customer ramp-up are the immediate milestones. G2 remains the next major capacity addition.
For Kaynes, Unit 2 and the Chennai PCB facility are the key near-term developments. Commercial revenue, customer qualification and the Mitsui relationship will show how quickly the new capacity develops.
For Dixon, component localisation remains central. Display and camera modules are already being developed, while the company is pursuing deeper manufacturing capabilities.
For Tata Elxsi, semiconductor-related growth will depend on engineering programmes and customer demand. Specialised talent, embedded technology and product-engineering capabilities remain central to that business.
Semiconductor stocks: Valuation comparison
| Ratio / stock metric | CG Power | Kaynes Technology | Dixon Technologies | Tata Elxsi |
| Face value | Rs 2.00 | Rs 10.00 | Rs 2.00 | Rs 10.00 |
| EPS-TTM | Rs 7.93 | Rs 51.57 | Rs 307.00 | Rs 105.08 |
| PE Ratio | 111.84x | 70.32x | 47.69x | 34.40x |
| PB Ratio | 16.89x | 5.06x | 16.62x | 7.01x |
| EV/EBITDA | 54.80x | 31.56x | 22.88x | 22.42x |
| Dividend/share | Rs 1.30 | Rs 0 | Rs 10.00 | Rs 75.00 |
| Dividend yield | 0.15% | 0% | 0.07% | 2.07% |
| Beta (1M) | 0.74 | 0.50 | 1.00 | — |
Source: Dion Global ratio analysis.
Conclusion
India’s semiconductor push is reaching these four companies through four different businesses.
CG Power has entered commercial OSAT production. Kaynes is bringing OSAT and PCB capacity into operation. Dixon is moving deeper into components. Tata Elxsi is building semiconductor-related engineering capabilities.
The next stage will be visible in customer additions, production volumes, and the pace at which new capacity begins contributing to the businesses.
Disclaimer: This article is based on publicly available information, company filings, management commentary, earnings-call transcripts, market data and government notifications cited in the copy. The views and analysis are for informational and educational purposes only and should not be construed as investment advice, a recommendation, solicitation or an offer to buy or sell any securities. Readers should consult a SEBI-registered investment adviser and conduct their own independent research before making investment decisions. Past performance is not indicative of future returns. Market prices, valuations, financial results and business prospects can change. The publication and author do not assume responsibility for investment decisions or losses arising from the use of this information.