



Sansera Engineering is increasingly moving beyond its traditional automotive-component identity, with aerospace, defence and semiconductor-related businesses emerging as the main drivers of its next growth phase. CLSA has initiated coverage on the company with an ‘Outperform’ rating and a target price of Rs 4,954, implying 31% upside.
The brokerage also sees potential for Sansera’s equity value to double over the next three years as its Aerospace, Defence and Semiconductor (ADS) business scales up. CLSA’s central argument is that Sansera is entering a period where faster-growing, higher-margin businesses could increasingly contribute to the overall revenue mix.
The brokerage expects revenue to compound at 21% annually during FY26-FY29, while earnings per share could grow at 30% over the next three years.
| Metric | CLSA view |
| Rating | ‘Outperform’ |
| Target price | Rs 4,954 |
| Implied upside | 31% |
| FY26-FY29 revenue estimate CAGR | 21% |
| FY26-FY29 ADS revenue estimate CAGR | 65% |
| FY26-FY29 non-auto revenue estimate CAGR | 46% |
ADS business emerges as the main growth engine
CLSA’s strongest conviction is around Sansera’s ADS business, which includes aerospace, defence and semiconductor-related applications. The segment accounted for 10% of revenue in FY26, up from 4% in FY21, and had an order book of Rs 4,400 crore at the end of 1QFY27.
Sansera Engineering expects to execute this order book over the next two to three years, translating into an annual revenue run rate of around Rs 1,200-1,500 crore. CLSA forecasts a 65% revenue CAGR for ADS during FY26-FY29, making it the fastest-growing part of the company.
The brokerage also sees a margin advantage. ADS operates at EBITDA margins of about 25-30%, compared with 17-18% for the automotive business. Asset turnover is also higher at around 2.0 times versus 1.3-1.4 times for the other segments.
CLSA said the ADS business could therefore become increasingly important to Sansera’s overall profitability as its contribution rises. It estimates ADS revenue’s share could increase to 24% by FY29 from 9.6% in FY26.
Aerospace gives Sansera a long runway
Aerospace is at the centre of the ADS opportunity. CLSA estimates India’s aerospace manufacturing industry could expand from Rs 13,000 crore in 2024 to Rs 25,700 crore by 2030, implying roughly 12% annual growth.
India currently accounts for only about 2% of the global aerospace value chain, according to the report. CLSA believes this leaves room for Indian suppliers to gain share as global original equipment manufacturers and Tier-1 suppliers diversify sourcing and expand their supplier bases.
The brokerage said “even modest market share gains could translate into a sizeable growth runway” for Indian aerospace suppliers. It expects Sansera to continue receiving new orders and ADS revenue to grow at a strong double-digit rate.
The opportunity spans aerostructures, landing systems, machined parts and precision components. Sansera’s existing expertise in precision forging and machining gives it an entry point into these higher-qualification businesses, according to CLSA.
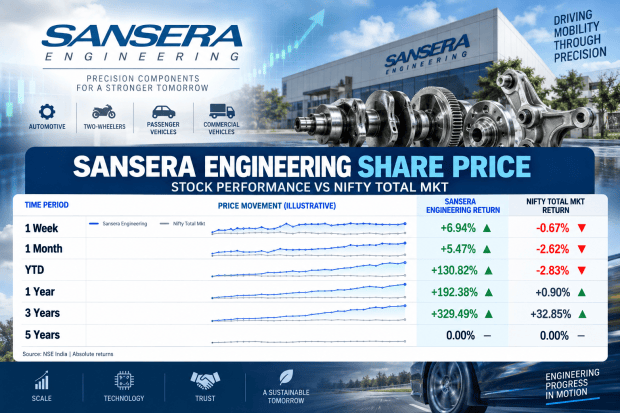
Sansera Engineering share price performance
Exports add another growth opportunity
Sansera already derives 35% of its revenue from exports, with 27% of total revenue coming from exports out of India and the remainder from Sweden. Export revenue grew at a 13% CAGR during FY22-FY26.
CLSA sees a multi-year opportunity from global automotive companies diversifying their supply chains. India is gaining interest because of its cost competitiveness, engineering capabilities and established manufacturing ecosystem, while forging remains a high-entry-barrier business because of qualification requirements and its role in safety-critical applications.
The brokerage believes Sansera’s experience in complex precision-engineered products and its growing international presence can help it win a larger share of export orders as global customers increase sourcing from India.
xEV business grows without betting on one technology
Sansera’s second major growth pillar is its auto-tech agnostic and electric vehicle-related business. This segment contributed about 13.5% of FY26 revenue, up from 5% in FY21.
The portfolio includes components for motors, chassis, suspension, transmission-related applications, structural parts and other engineered assemblies. Because many of these products can be used across internal combustion engine, hybrid and battery-electric vehicles, CLSA sees lower dependence on any single powertrain technology.
CLSA expects revenue from this segment to grow at a 31% CAGR during FY26-FY29, taking its revenue contribution to 17% by FY29 from 13.5% currently. The brokerage is also building in about 45% annual growth in domestic electric two-wheeler volumes and 40% growth in electric passenger-vehicle volumes during FY26-FY30.
Core automotive business still provides stability
Despite the push into aerospace and electrification, Sansera’s traditional automotive business remains important. CLSA expects the Auto-ICE segment to account for 54% of revenue by FY29, with motorcycles remaining its largest contributor.
The brokerage believes this gives Sansera a diversified base while the newer businesses scale up. It expects the core ICE business to deliver high-single-digit growth, supported by the company’s customer mix and continued exposure to motorcycles, where it sees slower electrification than in scooters.
This combination is central to the investment case: the established automotive business continues to generate cash flows, while ADS and xEV-related products provide faster growth.
Margins could expand as business mix changes
CLSA expects Sansera’s overall revenue to grow at a 21% CAGR from FY26 to FY29, with EBITDA growth outpacing revenue as higher-margin ADS products become a larger part of the mix.
The brokerage estimates EBITDA margins will increase to 22.0% in FY29 from 18.1% in FY26. It expects the ADS contribution to revenue to rise to 24% over the same period, while the segment’s higher asset turnover should also improve overall capacity efficiency.
| Financial metric | FY26 | FY27e | FY28e | FY29e |
| Revenue (Rs crore) | 3,498 | 4,176 | 5,091 | 6,193 |
| Net profit (Rs crore) | 324 | 445 | 621 | 824 |
| EPS (Rs) | 51.9 | 71.4 | 99.5 | 132.0 |
| EPS growth | 49.5% | 37.4% | 39.4% | 32.6% |
| EBITDA margin | 18.1% | — | — | 22.0% |
| ROE | 11.1% | 13.5% | 16.3% | 18.4% |
CLSA sees a 2x opportunity over three years
The brokerage’s longer-term view is more aggressive than its 12-month target. CLSA said “Sansera could be a 2x three-year story”, based on sustained high-teen revenue growth, ADS execution and continued expansion of the newer businesses.
CLSA expects earnings per share to compound at about 30% over the next three years, taking FY31 estimated EPS to around four times FY26 levels. On a 40-times forward price-to-earnings multiple, the brokerage’s three-year valuation framework points to an implied value of about Rs 7,687.
The brokerage’s 12-month target remains Rs 4,954, implying 31% upside, while its three-year framework indicates potential for a much larger gain if the expected earnings trajectory plays out.
Competition and execution remain key risks
CLSA’s view is not without risks. The Auto-ICE business is still expected to contribute more than half of revenue by FY29, leaving Sansera exposed to a faster-than-expected adoption of electric motorcycles. The brokerage’s base case assumes electrification will initially remain concentrated in scooters.
Competition in ADS is another concern. More auto-component companies are entering aerospace, defence and semiconductor manufacturing, which could increase competitive intensity and put pressure on margins over time.
Disclaimer: This article is based solely on CLSA’s Growth engine taking wings report on Sansera Engineering dated September 7, 2026. The information is provided solely for informational and educational purposes and should not be considered investment advice, a recommendation to buy, sell or hold any security, or a substitute for independent financial research. Brokerage estimates, earnings forecasts, valuation assumptions, target prices and ratings are subject to change and may differ from actual business or market outcomes. Stock market investments are subject to market risks, including the possible loss of principal. Past performance does not guarantee future returns, and projected earnings or returns may not materialise due to changes in economic conditions, company performance, interest rates, regulations, commodity prices, competition, liquidity and other factors. Readers should independently assess the information, consider their own financial circumstances, investment objectives and risk tolerance, and consult a qualified financial adviser before making any investment decision. Neither the author nor the publication assumes responsibility for any financial loss arising from reliance on the information presented in this article.