


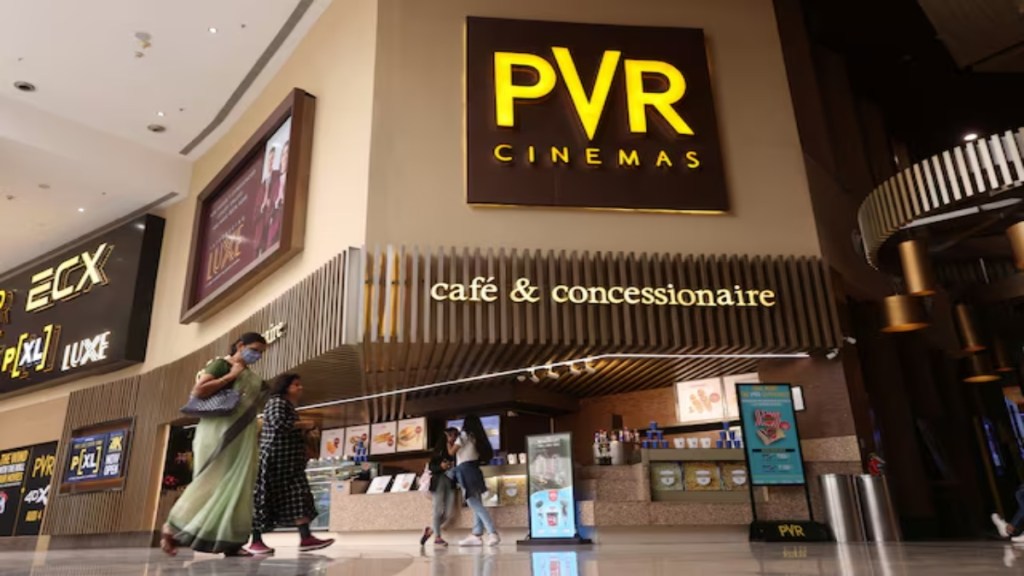

PVR Inox buyback: A cinema chain’s latest buyback has drawn attention, but two brokerages are pointing to a broader improvement in its business. Better attendance, stronger spending at theatres, a healthy movie pipeline and a much stronger balance sheet have improved the earnings outlook.
CLSA has retained its ‘Outperform’ call and sees 78% upside, while JM Financial has kept its ‘Add’ rating and raised its target. The two brokerages have different views on valuation, but both see room for the business to improve as content and operating performance strengthen.
CLSA on PVR Inox: ‘Outperform’
CLSA retained its ‘Outperform’ rating and a target price of Rs 2,135, implying 78% upside. The brokerage’s case rests on the recovery in cinema attendance, better customer spending and the scope for margins to improve as the business gets more operating leverage.
PVR Inox had a stronger first quarter, with admissions rising 8% year on year. Customers also spent more on both tickets and food and beverages. Movie-ticket sales increased 15%, while F&B sales rose 13%, and reported EBITDA grew 33%.
CLSA’s view was that the improvement in attendance and spending pointed to stronger underlying demand rather than a one-off increase in movie visits. The brokerage described PVR Inox as “a compelling play on discretionary consumption in India” and said multiplexes remained the country’s leading form of outdoor entertainment.
The margin opportunity is also important. PVR INOX Ltd. has been controlling utilities, manpower, rental and F&B costs, while better food offerings have helped improve customer spending. CLSA expects these efforts, along with higher occupancy, to support the recovery in profitability.
Strong content can support occupancy
The movie pipeline remains central to the CLSA view. The brokerage expects upcoming Hindi, regional and Hollywood releases to support attendance. It also noted that stronger regional and English-language films had supported the business when Hindi content was weaker.
PVR Inox’s premium formats give it another way to earn more from customers who choose higher-end cinema experiences. Management said premium screens had been helping raise average ticket prices, particularly as customers were willing to pay more for formats such as IMAX and other premium experiences.
Management put it this way: “When premium customers come, they want to see movies without compromises, obviously, and that also takes PVR Inox’s ATP up.”
CLSA also expects advertising income to normalise, which it identified as a short-term catalyst. Its main concerns were weaker movie content, slower mall additions and a slower recovery in advertising revenue.
Balance sheet gives room to expand
The buyback came after a significant improvement in PVR Inox’s financial position. The company had moved from net debt of Rs 161.9 crore at the end of FY26 to net cash of Rs 80.7 crore by the end of 1QFY27.
PVR Inox had also generated free cash flow for three consecutive years, according to CLSA. This allowed the company to fund part of its expansion internally rather than relying as heavily on additional borrowing.
The company plans to add around 100 screens in FY27, with asset-light and FOCO models accounting for a large part of the additions. CLSA noted that these formats had already helped the company expand while reducing pressure on the balance sheet.
The brokerage expects this approach to continue through FY27, with most new properties likely to use asset-light formats. It also sees nearly 300 tier-2 and tier-3 cities as potential markets where the company can expand its network.
JM Financial on PVR Inox: ‘Add’
JM Financial retained its ‘Add’ rating and raised its 12-month target price to Rs 1,270 from Rs 1,130, implying 5.1% upside. It also raised the EV/EBITDA multiple used in its valuation to 9 times from 8 times, citing the healthy content pipeline.
The brokerage viewed the buyback as a sign of greater confidence in the company’s balance sheet. PVR Inox had moved into net cash by June, while management continued to prioritise expansion.
The lower capital requirement of the newer expansion models was another positive. JM Financial noted that FY27 capex guidance had been reduced to Rs 350 crore from Rs 400 crore as asset-light and FOCO models gained traction. Management retained its plan for 90-100 gross screen additions.
JM Financial called the announcement “a notable capital-return milestone”, while maintaining that growth investments remained a priority.
Its earnings estimates point to a sustained recovery over the next three years. Adjusted net profit is expected to rise from Rs 227 crore in FY26 to Rs 467 crore in FY27 and Rs 902 crore in FY29, while ROIC is forecast to increase from 8.7% to 19.9% over the same period.
The brokerage summed up its revised stance by saying: “The buyback signals balance-sheet confidence; maintain ADD with revised target price of Rs 1,270.”
Live sports add another use for the theatre network
CLSA also pointed to live sports as an additional opportunity. PVR Inox had screened IPL matches and the FIFA World Cup across its theatres, allowing the company to use its network beyond regular movie releases.
The FIFA World Cup final drew 64,000 people across the chain, according to management. CLSA sees such events as another way for PVR Inox to generate footfall when the regular movie schedule is less supportive.
PVR Inox: CLSA more bullish than JM Financial
The biggest difference between the two reports is their valuation of the earnings recovery. CLSA sees a much larger re-rating opportunity, supported by stronger content, improving attendance, customer spending, operating leverage and asset-light expansion. JM Financial has also raised its valuation multiple, but its target remains far below CLSA’s.
The two views therefore point to the same operating areas without assigning the same value to them. For PVR Inox, the coming quarters will show whether the stronger movie pipeline can sustain attendance and whether the company’s newer expansion model can deliver growth while keeping capital requirements under control.
Disclaimer: This article is based on CLSA’s Share buyback and beyond movies report dated September 1, 2026, and JM Financial’s PVR INOX company update dated August 31, 2026. Ratings, price targets, estimates and brokerage views are subject to change and aren’t guarantees of future performance. This article is for informational purposes only and shouldn’t be treated as investment advice or a recommendation to buy or sell any security.