



JP Morgan expects India’s consumer discretionary sector to maintain steady growth in the second quarter of FY27, helped by premiumisation, store expansion, pricing actions and operating efficiencies. But the brokerage sees a more uneven earnings picture underneath the revenue numbers, with gold prices, raw-material costs, festive-season timing and higher operating expenses likely to determine how much of that growth reaches the bottom line.
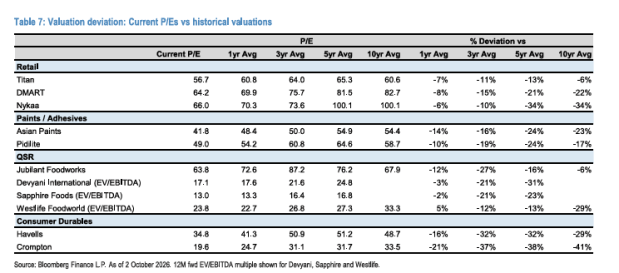
The brokerage’s preferred names are Titan, Lenskart, LG Electronics India and Pidilite Industries. It is also positive on Vishal Mega Mart, Devyani International, Sapphire Foods India and Westlife Foodworld . Avenue Supermarts, Nykaa, Jubilant FoodWorks, Havells India and Crompton Greaves Consumer Electricals are rated ‘Neutral’.
Among the companies under coverage, JP Morgan expects Lenskart and Nykaa to deliver the fastest revenue growth in the quarter. In contrast, the paints, consumer durables and quick-service restaurant segments could see greater pressure on margins as input costs remain elevated.
Festive demand is holding up, but the timing is different
The second quarter is usually an important period for discretionary consumption, but this year the comparison is being complicated by changes in the timing of festivals and weddings. That is particularly relevant for jewellery, fashion and beauty categories, where purchases can move between months depending on the festive calendar.
JP Morgan said, “Consumption trends remain broadly constructive across discretionary segments in the second quarter of financial year 2027, driven by premiumisation, formalisation, pricing actions, and value-led propositions. Festive timing shifts have affected seasonality across jewellery, fashion, and beauty and personal care.”
The brokerage expects the underlying demand environment to remain supportive, with organised retailers continuing to gain from a wider store network and greater penetration. Premiumisation is another support, particularly for jewellery, beauty and personal care and selected discretionary categories.
The important question for the quarter, however, is not simply whether companies grow revenue. It is how much of that growth survives higher input costs and operating expenses.
Titan: Gold prices and studded jewellery on its radar
Titan Company is expected to report 16% year-on-year revenue growth in the second quarter of FY27, with profit after tax projected to rise 20%, according to JP Morgan.
The brokerage expects domestic jewellery revenue across Tanishq, Mia and Zoya to grow 25%. It expects the jewellery segment’s earnings before interest and taxes margin to remain broadly stable at around 11%.
The backdrop is complicated by the sharp rise in gold prices. JP Morgan expects plain-gold purchases to have faced some pressure in September as consumers delayed purchases amid price volatility. Studded jewellery, however, has remained more resilient.
JP Morgan said, “While jewellery demand remained healthy in July-August, sharp gold price volatility in September appears to have weighed on buyer sentiment, leading consumers to defer purchases. Further festive shifts would have also affected growth in September.”
Titan has also been expanding its lower-ticket studded jewellery offering and strengthening its bridal portfolio through Tanishq Rivaah Wedding Signature. That gives the company more avenues to capture demand even as the timing of large jewellery purchases moves around.
JP Morgan rates Titan Company ‘Overweight’.
Lenskart : Emerging as one of the strongest growth stories
Lenskart is expected to be one of the fastest-growing companies in JP Morgan’s consumer coverage. The brokerage forecasts 29% year-on-year revenue growth in the second quarter of FY27 and 92% growth in profit after tax.
India revenue is expected to rise 32%, while international revenue is forecast to increase 25%. The brokerage expects earnings before interest, taxes, depreciation and amortisation margins before Indian Accounting Standards adjustments to reach 15.5% in India and 9.8% internationally.
The growth case is being driven primarily by volumes, while operating leverage and cost efficiencies are expected to support profitability.
JP Morgan said, “We expect Lenskart to sustain its solid growth trajectory and forecast 32% and 25% year-on-year growth for India and international businesses, driven primarily by volumes. We expect India and international pre-Indian Accounting Standards earnings before interest, taxes, depreciation and amortisation margins of 15.5% and 9.8% respectively, on the back of operating leverage and cost efficiencies.”
The brokerage rates Lenskart ‘Overweight’.
Nykaa is another high-growth name in the coverage universe, although JP Morgan takes a more cautious view on the stock. Revenue is expected to grow 27%, with profit after tax projected to rise 161%. Beauty revenue is forecast to increase 26%, while fashion revenue could grow 45%.
The brokerage expects Nykaa’s earnings before interest, taxes, depreciation and amortisation margin to expand by 140 basis points year-on-year to 8.4%, helped by scale benefits.
Nykaa is rated ‘Neutral’.
Value retail continues to find room to grow
Avenue Supermarts is expected to report 18% revenue growth in the second quarter, supported by its value proposition, pricing across staples and continued store additions.
JP Morgan expects the company to add 15 stores, taking the total to 518, with much of the expansion focused on smaller towns. The brokerage expects the earnings before interest, taxes, depreciation and amortisation margin to improve modestly to 7.7%.
JP Morgan said, “We forecast Avenue Supermarts to clock 18% revenue growth driven by its strong value proposition in an inflationary environment, price increases across staples and accelerated store additions of 15, taking the total to 518 stores, primarily in smaller towns. We build in a modest expansion in earnings before interest, taxes, depreciation and amortisation margin to 7.7% as scale benefits are largely offset by higher operating expenses.”
The brokerage expects Vishal Mega Mart to deliver 17% revenue growth. Its margin, however, is expected to contract by 20 basis points year-on-year to 13%, largely because of a lower gross margin. Sourcing and operating efficiencies should provide some offset.
JP Morgan rates Avenue Supermarts ‘Neutral’ and Vishal Mega Mart ‘Overweight’.
| Company | JP Morgan rating | Q2FY27E revenue growth | Key factor |
| Titan Company | ‘Overweight’ | 16% | Jewellery growth and resilient studded demand |
| Lenskart | ‘Overweight’ | 29% | Volume growth and operating leverage |
| LG Electronics India | ‘Overweight’ | 15% | Pricing-led growth |
| Pidilite Industries | ‘Overweight’ | 19% | Strong volume growth despite cost pressure |
| Vishal Mega Mart | ‘Overweight’ | 17% | Store growth and sourcing efficiencies |
| Avenue Supermarts | ‘Neutral’ | 18% | Store additions and value positioning |
| Nykaa | ‘Neutral’ | 27% | Beauty and fashion growth |
| Asian Paints | ‘Overweight’ | 14% | Pricing and volume growth, but margin pressure |
| Havells India | ‘Neutral’ | 20% | Cables and wires growth |
| Crompton Greaves Consumer Electricals | ‘Neutral’ | 9% | Moderate growth across segments |
| Jubilant FoodWorks | ‘Neutral’ | 10% | Demand recovery offset by cost pressure |
| Devyani International | ‘Overweight’ | 12% | Kentucky Fried Chicken growth |
| Sapphire Foods India | ‘Overweight’ | 17% | Kentucky Fried Chicken growth |
| Westlife Foodworld | ‘Overweight’ | 14% | Value initiatives and footfall recovery |
Paint companies face a tougher profitability test
Asian Paints is expected to post 14% revenue growth in the second quarter, with domestic volume growth estimated at 6%. Pricing and product mix are expected to contribute 8% to revenue growth as earlier industry-wide price increases flow through.
But the revenue growth comes with a margin trade-off. JP Morgan expects the company’s earnings before interest, taxes, depreciation and amortisation margin to decline 70 basis points year-on-year to 16.9%, largely because of higher-cost inventory.
JP Morgan said, “We forecast Asian Paints revenue growth of 14% year-on-year, with domestic volume growth of 6%, primarily driven by price and mix gains of 8% as industry-wide price hikes flow through, offset to some extent by adverse mix. Despite pricing actions, we expect earnings before interest, taxes, depreciation and amortisation margin to contract 70 basis points year-on-year to 16.9%, reflecting the impact of higher-cost inventory, partly offset by price hikes, backward integration benefits, and ongoing cost-efficiency initiatives.”
Pidilite Industries presents a different mix. Revenue is expected to rise 19%, supported by about 10% volume growth, but the earnings before interest, taxes, depreciation and amortisation margin is expected to fall to 20.8%, a 310-basis-point year-on-year decline.
JP Morgan remains positive on both companies and rates Asian Paints and Pidilite Industries ‘Overweight’.
Consumer durables have pricing support, but costs are rising
LG Electronics India is expected to report 15% revenue growth and 23% growth in profit after tax in the second quarter. JP Morgan expects pricing to remain an important contributor to revenue, while the company continues to deal with higher raw-material costs.
The brokerage forecasts an earnings before interest, taxes, depreciation and amortisation margin of 9.6%, up 70 basis points year-on-year, although that would be 290 basis points lower sequentially.
JP Morgan said, “Revenue growth trends remain steady, benefiting from increased pricing. However, inflationary raw-material costs will weigh on profitability. We expect LG Electronics India to sustain its growth momentum and deliver revenue growth of 15% year-on-year.”
Havells India is expected to report 20% revenue growth, led by pricing-driven growth in cables and wires. Its earnings before interest, taxes, depreciation and amortisation margin is forecast at 9%, down 20 basis points year-on-year.
Crompton Greaves Consumer Electricals is expected to post 9% revenue growth, with JP Morgan focusing on segment-level performance and the progress of newer businesses such as wires and rooftop solar.
LG Electronics India is rated ‘Overweight’, while Havells India and Crompton Greaves Consumer Electricals are rated ‘Neutral’.
Restaurant chains are seeing demand improve, but costs are eating into margins
Quick-service restaurant companies are beginning to see better demand, helped by value-led offers designed to bring customers back more frequently. JP Morgan expects like-for-like sales growth at Jubilant FoodWorks to improve to 3-4%, Kentucky Fried Chicken same-store sales growth to around 4-5% and Westlife Foodworld same-store sales growth to around 6%.
The pressure is coming from the cost side. Milk, cheese, chicken and edible oil remain important inputs, while higher wages and fuel costs are also weighing on restaurant margins.
JP Morgan said, “Quick-service restaurant players are witnessing improving demand trends, supported by value-led initiatives to drive footfalls. However, inflation in key inputs such as milk, cheese, chicken, and edible oil, alongside higher wages due to minimum wage hikes across multiple states and fuel costs, is likely to weigh on margins.”
Jubilant FoodWorks is expected to report 10% revenue growth and 8% profit-after-tax growth. Devyani International is expected to grow revenue 12%, Sapphire Foods India 17% and Westlife Foodworld 14%.
JP Morgan rates Jubilant FoodWorks ‘Neutral’, while Devyani International, Sapphire Foods India and Westlife Foodworld are rated ‘Overweight’.
The input-cost picture could decide the margin winners
The raw-material data in JP Morgan’s report offers a useful explanation for the gap between revenue growth and profitability across the sector.
Crude oil was at US$102 a barrel as of October 2, 2026, according to the report, after rising 41.7% over one month. High-density polyethylene was up 42.6% over the same period, while polyethylene terephthalate had risen 49.2%. Copper prices were up 7.2% over one month.
Gold was at Rs 147,770 per 10 grams, up 10.2% over six months and 26.9% over one year. That sharp increase has a direct bearing on jewellery demand, particularly for customers who can defer purchases.
For consumer companies, therefore, pricing power and cost control could be just as important as the headline revenue growth rate. Companies with stronger scale, better sourcing or the ability to pass on higher costs have a better chance of protecting margins.
JP Morgan’s preferred picks
JP Morgan’s preferred names bring together four different consumption stories.
The brokerage said, “Overall, we expect second-quarter growth to be supported by premiumisation, store expansion, pricing-led gains, and operating efficiencies, with margin outcomes varying based on companies’ ability to offset cost pressures. Among our coverage universe, Lenskart and Nykaa will post the highest growth rates in the second quarter. Our preferred picks include Titan Company, Lenskart, LG Electronics India and Pidilite Industries.”
The broader message from the report is that consumer demand itself is not the main concern for the quarter.Festive and wedding demand should provide a seasonal lift, but the benefits will not be evenly distributed. Jewellery is dealing with unusually high gold prices, paints and adhesives face raw-material pressure, consumer durables are seeing higher input costs and restaurant chains are contending with food, wage and fuel inflation.
Disclaimer: This article provides factual analysis only and is not, and should not be construed as, an offer, solicitation, or recommendation to buy or sell securities. Investors must conduct their own independent due diligence and seek advice from a SEBI-registered financial advisor.