



India’s large banks are entering a stronger credit cycle, but BofA Securities sees the recovery playing out differently across State Bank of India, ICICI Bank, HDFC Bank and Kotak Mahindra Bank. The brokerage remains positive on all four, with growth, funding strength, margins and asset quality shaping the case for each bank.
BofA expects the improving liquidity environment to support loan demand. Its latest research points to ICICI Bank’s ability to outgrow the industry, SBI’s funding advantage, HDFC Bank’s improving fundamentals and Kotak Mahindra Bank’s recovery-led growth opportunity. The brokerage has a ‘Buy’ rating on all four stocks.
BofA on SBI: ‘Buy’
SBI’s strength, according to BofA, lies in its funding franchise and balance-sheet position as credit demand improves.
“SBI continues to deliver robust loan growth and healthy RoA. We believe that with its superior funding franchise, lower domestic LDR and healthy demand in corporate/SME, SBI appears well positioned to sustain healthy loan growth,” BofA said.
The brokerage also sees SBI as relatively well placed for the transition to expected credit loss-based provisioning, citing its provision buffers and low slippage levels.
BofA retained its ‘Buy’ rating and price objective of Rs 1,250, implying 26% upside.
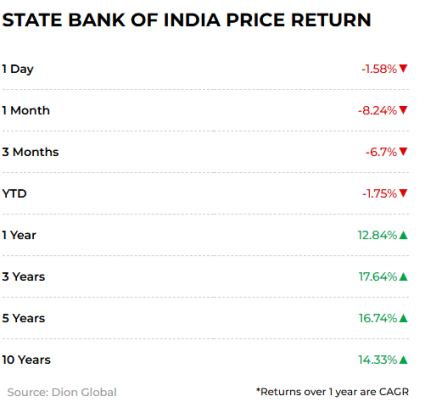
SBI share price performance
BofA on ICICI Bank: ‘Buy’
ICICI Bank is taking a different route, with BofA expecting it to keep growing faster than the broader industry.
“After a temporary slowdown in loan growth in early FY26, ICICI Bank has re-emerged as one of the fastest-growing large private banks,” the brokerage said.
BofA expects ICICI Bank to sustainably outgrow the industry by around 2-3%, supported by its business banking and retail franchises. The brokerage also expects the bank to maintain broadly stable NIMs and sees scope for further support from a possible rate hike and a recovery in unsecured lending.
BofA said the bank’s execution across growth, profitability and asset quality supports a valuation premium to peers.
It retained its ‘Buy’ rating and raised the price objective to Rs 1,650 from Rs 1,600, implying 23% upside.
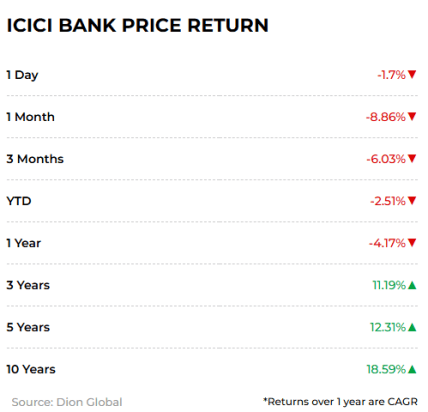
ICICI Bank share price performance
BofA on HDFC Bank: ‘Buy’
For HDFC Bank, the focus is on whether the recent improvement in its operating performance can translate into a sustained recovery in loan growth.
“Fundamentals continue to improve, supported by a pick-up in loan growth, healthy deposit momentum and a surplus system liquidity environment,” BofA said.
The brokerage also sees potential support for NIMs from a possible rate hike and expects RoA to improve beyond 2% over time, helped by a better loan mix and operating leverage.
At the same time, BofA said the CEO transition remains an important near-term factor, with greater clarity on the transition needed before the next phase of valuation expansion.
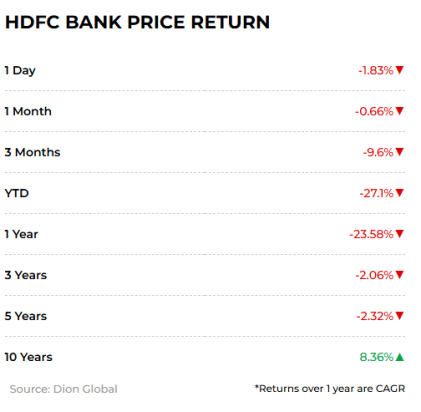
The brokerage retained its ‘Buy’ rating and Rs 880 price objective, implying 21% upside.
BofA on Kotak Mahindra Bank: ‘Buy’
Kotak Mahindra Bank’s case is centred on a stronger loan-growth cycle and a recovery in unsecured retail lending.
BofA expects Kotak’s loan book to grow 15-16% annually over FY26-28, helped by healthy system credit growth, the bank’s higher growth sensitivity during upcycles and a recovery in unsecured retail from a low base.
“We expect RoA to increase from 1.9% in FY26 to 2.2% by FY28 led by better NIM and normalized credit cost,” the brokerage said.
BofA also pointed to Kotak’s proposed acquisition of Deutsche Bank’s India business as a source of additional capital deployment. Greater clarity around the CEO transition could also provide a near-term trigger, according to the brokerage.
It retained its ‘Buy’ rating and raised the price objective to Rs 500 from Rs 460, implying 20% upside.
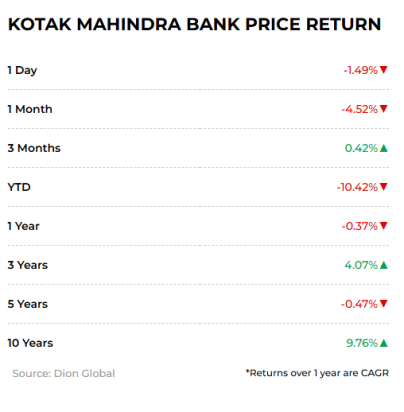
Kotak Mahindra Bank share price
Four banks, four distinct growth stories
BofA’s latest assessment puts the four banks in the same ‘Buy’ camp, but for different reasons.
SBI’s case is built around funding strength and sustained loan growth. ICICI Bank is being backed for its ability to grow ahead of the industry while maintaining strong profitability. HDFC Bank is being assessed on its improving loan and deposit trends, while Kotak’s opportunity is tied to credit growth, unsecured retail recovery and improving returns.
The broader backdrop is supportive. BofA said bank credit growth had reached around 20% year-on-year by August-end, with system liquidity improving substantially after sizeable inflows. The brokerage expects surplus liquidity and festive-season demand to support loan growth, although it also sees some moderation from the current base.
One near-term pressure point is margins. BofA expects elevated FCNR deposit mobilisation in the second quarter to weigh on reported NIMs, while seeing potential improvement later as banks make better use of FCNR deposits and if a repo rate hike supports margins.
For the four banks, therefore, BofA’s latest report points to a common credit-growth backdrop but distinct company-specific drivers, ranging from SBI’s funding franchise and ICICI Bank’s growth momentum to HDFC Bank’s recovery and Kotak’s improving return profile.
Disclaimer: This article is based solely on the BofA Global Research report. The ratings, price objectives, earnings estimates, valuation assumptions and projections cited are those of BofA Securities and its analysts. These estimates are subject to changes in economic conditions, interest rates, liquidity, regulation, credit growth, asset quality and company-specific developments, and actual outcomes may differ. BofA Securities has also disclosed business relationships with companies covered in its research.