



Brokerage consensus stock picks: Brokerages are taking a constructive view on a handful of Indian stocks, with several names receiving ‘Buy’, ‘Outperform’ or similar positive ratings from more than one research house. The calls cover banks, IT services, airport operations and digital insurance distribution, with brokerages pointing to earnings growth, business expansion, leadership changes and improving operating metrics.
HDFC Bank has drawn positive views from Jefferies, Nomura, Bernstein and Macquarie, while Coforge has received ‘Buy’ calls from Jefferies and Motilal Oswal. GMR Airports has a ‘Buy’ call from Emkay and an ‘Outperform’ rating from Macquarie.
HDFC Bank
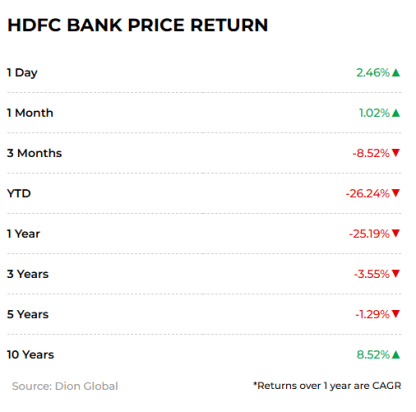
Jefferies on HDFC Bank: ‘Buy’
Jefferies has retained its ‘Buy’ rating on HDFC Bank with a target price of Rs 880, implying around 24% upside. The brokerage said the board has moved quickly on the succession process after submitting two names to the RBI for a three-year CEO term.
Jefferies said an internal appointment could make the transition easier because the candidate would already be familiar with HDFC Bank’s operations. The brokerage identified Deputy Managing Director Kaizad Bharucha as a key internal candidate and said he could have around 2.8 to three years of tenure eligibility.
The brokerage also said confirmation of the next CEO before Sashidhar Jagdishan’s term ends on October 26 could reduce concerns around business momentum. Jefferies noted that HDFC Bank trades at a discount to ICICI Bank and Kotak Mahindra Bank on FY27 adjusted price-to-book valuation.
Nomura on HDFC Bank: ‘Buy’
Nomura has retained a ‘Buy’ rating on HDFC Bank with a target price of Rs 950, implying around 34% upside. The brokerage said the two candidates submitted to the RBI could lead to different outcomes depending on whether the eventual appointment is internal or external.
Nomura said an internal appointment could provide continuity and limit disruption, particularly because of the candidate’s familiarity with the bank and its businesses. At the same time, the brokerage said a credible external candidate could bring a longer runway and provide greater scope to reassess strategy.
Bernstein on HDFC Bank: ‘Outperform’
Bernstein has assigned an ‘Outperform’ rating to HDFC Bank with a target price of Rs 1,150, implying around 62% upside. The brokerage focused on the timing of the board’s succession process, noting that the names have been submitted to the RBI well before the end of Jagdishan’s term.
Bernstein said the board is seeking a three-year term for the incoming CEO while also proposing the elevation of Jimmy Tata as a whole-time director and the creation of another whole-time director position. This would take the number of whole-time directors to four, excluding the MD and CEO.
Macquarie on HDFC Bank: ‘Outperform’
Macquarie has assigned an ‘Outperform’ rating to HDFC Bank with a target price of Rs 1,150, implying around 62% upside. The brokerage said the board’s latest actions provide some reassurance around succession, although the final CEO appointment remains the more important development.
Macquarie said adding another whole-time director gives HDFC Bank greater depth in its senior management structure and makes succession planning more institutional. The brokerage said the incoming CEO will be consulted on filling the additional position.
Coforge
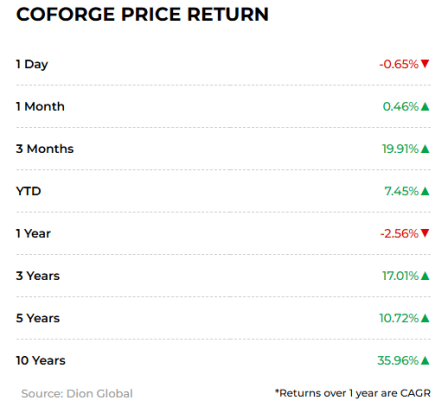
Jefferies on Coforge: ‘Buy’
Jefferies has retained its ‘Buy’ rating on Coforge with a target price of Rs 2,040, implying 15% upside.. The brokerage said the recent boardroom developments have had limited impact on Coforge’s growth strategy.
The company has reiterated its FY27 guidance, including a consolidated EBITDA margin target of 20.5% to 21%, at least 15.5% consolidated EBIT margin and 100%+ free cash flow to PAT conversion. Coforge has also retained its longer-term aspiration of reaching around $5 billion in revenue.
Motilal Oswal on Coforge: ‘Buy’
Motilal Oswal has assigned a ‘Buy’ rating to Coforge with a target price of Rs 2,200, implying 23% upside. Its report focuses on Coforge’s enterprise AI strategy and the company’s attempt to move from AI experimentation towards wider deployment inside large enterprises.
Motilal Oswal also pointed to Coforge’s large executable order book and the potential for outcome-based pricing to become more important as the cost of AI model access falls. The brokerage sees the company’s ability to combine data readiness, AI operations and engineering talent as an important part of its growth opportunity.
Nomura on Coforge: ‘Buy’
Nomura has retained a ‘Buy’ rating on Coforge with a target price of Rs 1,860. Its September 17 report focuses on the company’s enterprise AI strategy and the development of its Nuuron platform.
Nomura said model intelligence is becoming cheaper while enterprise context, data and governance are becoming more valuable. It believes Coforge is positioning itself around this gap through Nuuron, Momentuum Blue and its Data Cosmos platform.
GMR Airports
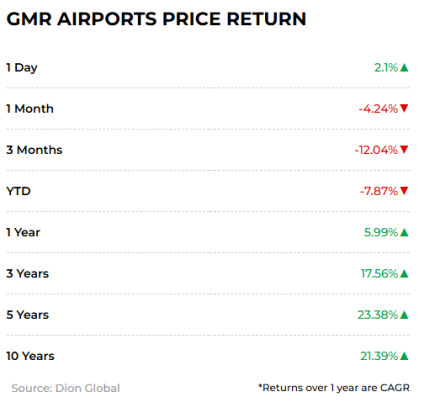
Emkay on GMR Airports: ‘Buy’
Emkay has initiated coverage on GMR Airports with a ‘Buy’ rating and a target price of Rs 120, implying about 25% upside. The brokerage said the company is building a broader airport business by expanding its non-aeronautical operations alongside passenger traffic.
The brokerage pointed to duty-free, cargo, car parking and retail as areas where GMR is taking greater control across its airport portfolio. Emkay said the GAL platform provides GMR with a dedicated vehicle to scale and monetise these non-aero opportunities.
Emkay also noted that GMR Airports assumed full control of duty-free operations at Delhi and Hyderabad airports and cargo operations at Delhi Airport during FY26. Revenue from the standalone GAL platform increased to Rs 4,200 crore in FY26 from Rs 1,300 crore in FY25, according to the brokerage.
Macquarie on GMR Airports: ‘Outperform’
Macquarie has an ‘Outperform’ rating on GMR Airports with a 12-month target price of Rs 120. Its report puts the 12-month total shareholder return at 29%.
The brokerage said GMR’s investment case extends beyond the performance of its core airport operations. It sees the company combining airport operations with commercial opportunities linked to passengers and airport infrastructure.
Macquarie also pointed to the company’s improving profitability, simplified structure and passenger mix. The brokerage expects revenue and profitability to increase through FY29E, supported by the airport portfolio and expansion of commercial activities around those assets.
Conclusion
Brokerages remain positive on HDFC Bank, Coforge and GMR Airports, with their calls supported by factors ranging from leadership transition and AI-led growth to stronger airport monetisation. Target prices across the three stocks point to further upside, though the underlying triggers and timelines differ for each company.
Disclaimer: The information presented in this article is based on brokerage reports, research notes and publicly available market information cited in the story. The target prices, ratings and upside percentages mentioned are the views and estimates of the respective brokerages and are subject to change based on business performance, market conditions, valuation assumptions and other factors. These estimates should not be treated as guaranteed returns or as a prediction of future stock prices. Equity markets are subject to market, economic, regulatory, interest-rate and company-specific risks, and actual performance may differ materially from brokerage expectations. Readers should independently evaluate the financial position, valuation, growth prospects and risks associated with any stock before making an investment decision. This article is intended for informational and educational purposes only and should not be construed as investment advice, a recommendation to buy or sell any security, or a substitute for advice from a qualified financial adviser. Past performance does not guarantee future results, and investors should consider their own financial objectives, risk tolerance and investment horizon before taking any investment decision.