


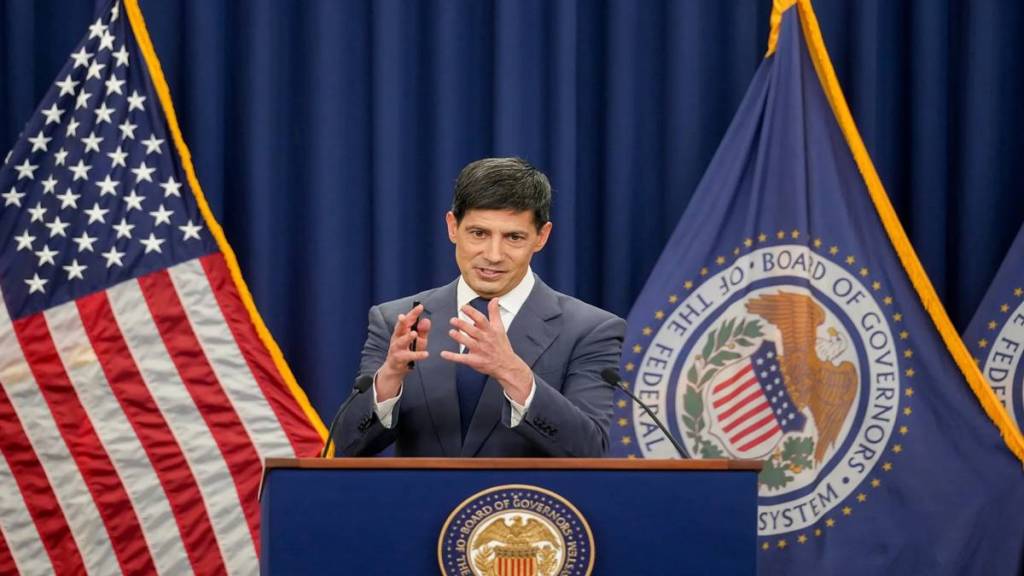

The odds of the US Fed raising interest rates at the next FOMC meeting are rising. According to CME Fed Watch, the futures market expects a 60% possibility of a rate hike announcement by US Fed chair Kevin Warsh on September 16. However, a scenario for a rate pause is also emerging.
The payrolls report from Friday will be in focus. While a stronger print would keep the potential of a raise firmly in play and may push yields higher once more, a weaker number would strengthen the case for the Fed keeping rates steady in September.
Inflation and oil prices continue to be impacted by the ongoing tensions between the US and Iran. Oil prices have breached $96 and have risen over 20% in the last month.
The Bigger Concern
Markets are concerned about the contrasting strategies of US Fed Chair Warsh and Treasury Secretary Bessent. Warsh aims to reduce inflation via rate hikes, while Bessent plans to double bond buy-back operations to increase liquidity and lower yields.
Bessent argues that the increase in yields is due to energy supply shocks linked to the ongoing conflict with Iran, rather than a failure in the market, and suggests that the Federal Reserve should not raise interest rates in response.
Investors are concerned not only about Iran-led inflation but also about the increasing US debt burden. The US debt has reached $40 trillion, with the budget deficit at alarming levels. This year, the debt interest burden has exceeded $1 trillion, surpassing the GDP of most countries.
But why are markets expecting a rate hike?
Inflation is the key factor influencing market expectations, which remain high despite persistent inflationary pressures. Both the US CPI and PPI data continue to show stickiness and remain much above the 2% target of the US Fed.
In his debut speech at Jackson Hole as Federal Reserve chair, Kevin Warsh himself acknowledged that fighting inflation is one of his priorities. With oil once again on the boil, with prices jumping 20% in the last month, breaching the $95 mark, the inflationary concerns linger on.
The case for a pause is just as strong
But, easier said than done, the factors pointing towards a rate pause are equally strong. Manufacturing activity cooled last month, with the ISM index slipping to 54.6, below the forecast of 55.2, and job openings also shrank, coming in at 7.27 million. A rate hike in the backdrop of such weakness could work against the economy.
However, the ISM index numbers may not be as disappointing as they look. Despite the slowdown, the reading still points to expansion, since any level above 50 signals growth, and August marked the eighth straight month of expansion for the sector.
Still, inflationary concerns are keeping the expectation of a rate hike alive this month. The Fed’s hawkish tone from last week’s Jackson Hole speech, combined with Iran-driven inflation concerns from rising oil prices, is simply outweighing ISM and job data. Until that changes, mixed economic numbers alone aren’t enough to ease rate hike expectations.
Meanwhile, on Wednesday, Federal Reserve Bank of New York President John Williams indicated that the increase in long-term bond yields reflects a strong economy rather than inflation fears. He noted that inflation is easing as tariff effects diminish, while the rise in energy prices has not significantly affected other services.
Bond yields are already telling their own story
A global sell-off has impacted sovereign bond markets, resulting in yields in Japan, the US, Germany, the UK, and France reaching multi-decade highs. On September 1, a sell-off in global bond markets escalated, with Japan’s 10-year bond yield reaching 3% for the first time since 1996. Globally, investors are dumping government securities, sending yields higher.
The rising bond yields are sending a signal that rates, at least on the longer-term securities, are going to remain higher. Longer-term inflation expectations and concerns over the US fiscal debt burden are making investors demand higher rates to hold US Treasury bonds.
The US 10-year Treasury bond yield is at 4.77% on Thursday, approaching its highest level since October 2023, with a potential climb toward 5% likely to disturb the already anxious stock markets. The 30-year US Treasury yield topped 5.33% mid-August, a level last seen in June 2007, and is currently at 5.25%.
What comes next, and when
But the action extends beyond the US Federal Reserve. The Bank of Japan’s monetary policy meeting is scheduled for September 17–18, 2026, amid expectations of a possible interest rate hike. Additionally, the US Treasury buy-back operation starts on September 9, which means peak volatility could hit markets in mid-September unless government interventions occur.
What happens next will define the next course of action for the US Fed and the markets, at least in the short term. US CPI data for August will be released on September 11, before the next FOMC meeting on September 15–16.
Disclaimer: This article is for informational purposes only and should not be considered investment advice. Readers should consult a financial advisor before making any investment decisions. Market forecasts and analyst projections mentioned are subject to change and are not guarantees of future performance.