


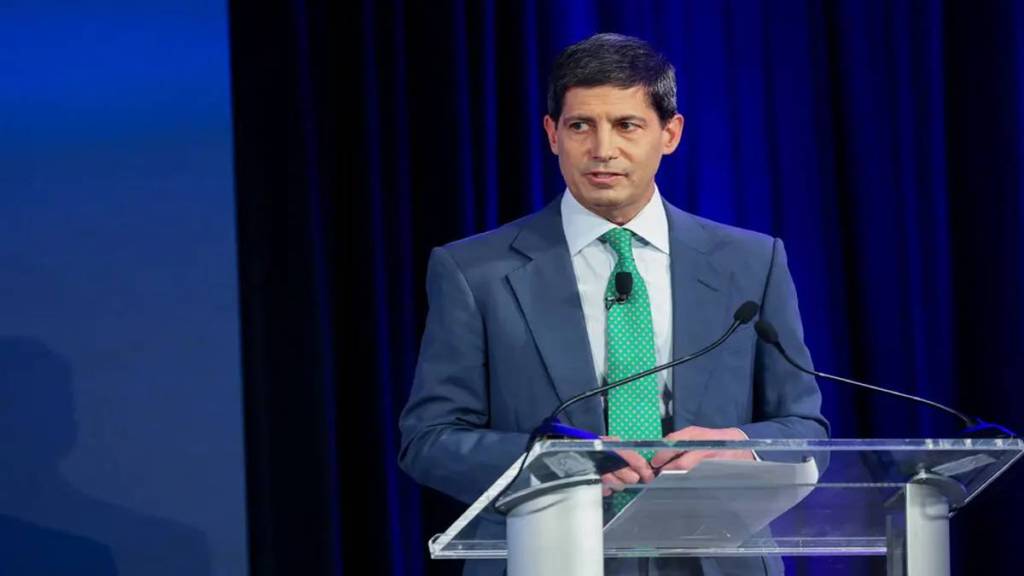

Federal Reserve Chairman Kevin Warsh delivered his first Jackson Hole keynote on August 28, marking his 100th day in office. Titled “In Our Time,” the speech touched on artificial intelligence, the future of forward guidance, his own guiding principles for monetary policy, and a candid read on where the US economy stands today.
Federal Reserve Chairman Kevin Warsh’s first Jackson Hole speech has disappointed gold investors, leading to a sharp decline in gold prices, which fell over 1.5% to approximately $4,535.
Here are the five big takeaways.
1. He wouldn’t call it forward guidance, but he all but handed out a trail map
In his Jackson Hole speech on Friday, Fed Chair Kevin Warsh refrained from endorsing either a reaction function or forward direction for monetary policy.
He laid out an outline of his remarks, AI, forward guidance, his policy principles, and his economic assessment, and joked, “you can call it an outline . . . you can call it a trail map . . . just don’t call it forward guidance.” It set the tone for a speech built around one central idea: less signaling, more discipline.
2. Forward guidance, in his view, has “overstayed its welcome”
Warsh traced forward guidance back to the Global Financial Crisis, when it was adopted as an emergency tool. He argued the practice was essential then but does not belong in normal times, where it “risks creating ambiguity in the name of clarity.”
His sharpest line: when policymakers make quasi-commitments on rates through the cycle, they end up limiting their own freedom to make the right call when a decision is actually due.
3. He wants markets reading the economy, not reading the Fed
Rather than spelling out a reaction function, Warsh called for clear, unfiltered market signals- asset prices, Treasury yields, the dollar, credit conditions, and commodity prices- to inform the Fed’s outlook.
At the same time, he wants market participants drawing their own conclusions instead of waiting on Fed cues. He described the alternative as a “hall of mirrors,” where the Fed leans on markets and markets lean on the Fed, leaving both blind to real shifts in the economy.
His warning carried a populist edge: if the Fed gets inflation or the economy wrong, it isn’t the financial elite who absorb the damage; it’s working Americans facing high prices or shakier jobs.
4. Seven principles now guide his approach to policy
Warsh laid out a personal framework for monetary policy. Among the highlights: don’t mistake yesterday’s data for today’s reality, trends matter more than isolated data points, the 2 percent PCE inflation target is firm and non-negotiable, the dual mandate isn’t a tradeoff, short-term rates remain the primary tool, and money supply still matters even if it’s out of fashion to say so.
He closed the list with a call for a “quieter Fed,” one that is more purposeful in its communication and judged by results rather than explanations.
5. His own read: Jobs are stable, but inflation still isn’t behaving
Warsh described an economy that has proven resilient, with capital expenditure up roughly 9 percent over four quarters, corporate profits up more than 20 percent, and unemployment holding at 4.1 percent.
But he flagged inflation as the Fed’s central concern. PCE inflation stands at 3.7 percent on a 12-month basis and 4.1 percent over six months, with more than half of the goods and services in the PCE basket still showing price increases above 3 percent. His conclusion: “I stand here today committed to a discipline, not to a decision.”
Bottomline
The speech avoided discussing the Treasury’s bond buyback program and the tensions between Warsh and Treasury Secretary Scott Bessent regarding long-term yields, an issue highlighted by economists as crucial for market interpretation.
Financial markets are responding variably: bond yields have increased, indicating expectations of higher future rates, while gold and silver prices are under pressure. Meanwhile, US stock markets remain nearly flat but show a slight positive trend.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Market conditions and asset prices can change rapidly. Readers should conduct their own research and consult a qualified financial adviser before making investment decisions.