



The $160.7 trillion global bond market is sending a loud signal. Something investors have brushed aside for a long time may now be too big to ignore. Investors globally are selling bonds, hammering prices down and sending yields higher. And rising yields are bad news for almost everyone. From equity market investors to gold investors to common borrowers, all are going to get the pinch.
The 30-year US Treasury yields have reached their highest levels since 2002, with 20-year Treasury also at a post-2006 high, and 10-year yields at levels not seen since 2007. The 30-year Treasury bond is a long-dated security, making it more sensitive to interest rate expectations, which touched 5.33% this week, a level last seen in 2007. The 10-year Treasury yield has risen above 4.7%.
This is not a small, one-country problem. The surge in bond yields is not just restricted to the US but has spread across major economies. Bond yields in the UK, France, Italy, Germany and Japan, amongst others, are at a new high.
What’s Actually Pushing Yields Higher?
Why have US Treasury yields spiked? That’s because investors globally are selling off some of their existing bond holdings. Here’s how it works: with markets anticipating rates to move higher, investors start dumping their existing holdings, since older bonds with lower fixed coupons become less attractive. This selling pushes bond prices lower, and because bond yields move inversely to prices, yields rise.
But why are investors dumping bonds and expecting interest rates to remain higher, or even move up? There are several interconnected factors at work rather than just one. Still, one issue sits at the centre of almost all of them. Central to all of them remains the US-Iran war and the blockage of the Strait of Hormuz.
The Iran war is keeping oil prices higher, keeping inflationary pressures strong. That leaves no space for Kevin Warsh and the US Fed to cut rates, unless inflation trends lower. On top of all this, the US fiscal position continues to deteriorate. Each of these factors feeds into the other, and together they explain why yields keep climbing.
Markets Are Betting Rates Stay High
US CPI data released last week shows falling inflationary concerns. But it remains untamed. July’s inflation data at least removed the possibility of a September rate hike, but elevated oil prices point towards a rate hike in the US Fed FOMC meeting in October or in December. But wait, it’s not an easy move for the US Fed. Recent job market data indicated weakness, which may keep the US Fed away from any rate hikes.
Higher-for-longer rate sentiments are global. Japan possesses a significant amount of US Treasuries, but changes in interest rates are anticipated, with a potential hike in September or October. This may narrow the interest rate differential between the US and Japan, leading to Japanese investors selling off US Treasuries in favor of Japanese bonds.
In simple terms, if Japan offers better returns at home, Japanese money has less reason to stay parked in US debt. A sell-off by Japanese investors sends US bond yields higher, which has happened at least in two instances recently.
Oil Prices Are Making the Fed’s Job Harder
Since the US-Iran ceasefire agreement failed to get extended, the inflationary pressure has increased. Oil continues to trade above $91. “Every dollar added to the oil price makes the inflation argument harder for the Federal Reserve and easier for the bond vigilantes,” says Nigel Green, CEO, deVere Group.
“A central bank trying to cut into an inflation backdrop that refuses to cooperate is a central bank that loses credibility with the people buying its government’s debt, and once credibility goes, yields stop reflecting growth expectations and start reflecting a demand for compensation,” adds Green.
The US Is Spending More Than It Earns, and It’s Getting Costlier
The other big factor pushing yields higher is the increasing US fiscal deficit. US spends more than its revenues, and the gap is widening.
The federal government has spent $1.80 trillion more than it has collected year-to-date in fiscal year (FY) 2026. The U.S. fiscal deficit jumped to $432.3 billion in July, its highest monthly total since March 2021.
The total national debt for the US continues to rise and is close to $40 trillion. US is spending over a trillion dollars each year to service its debt. As of July 2026, it costs $1.17 trillion to service the debt, which is 19% of total federal spending for fiscal year 2026.
“A government paying more than $1 trillion a year just to service debt, with a fresh wave of long-dated issuance still to come, is a government whose bond buyers get to set the terms. Investors are no longer taking it on faith that spending will be brought under control. Indeed, they’re pricing the risk that it doesn’t,” says Nigel Green, CEO, deVere Group.
Here’s the US debt position, as of September 2025
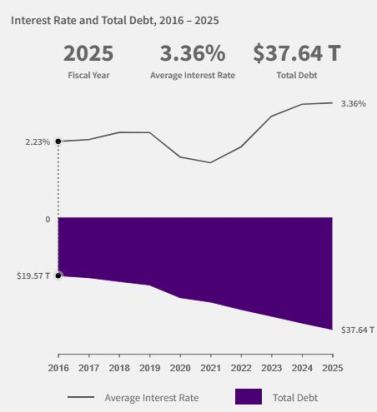
Source: fiscaldata.treasury.gov
Gold Is Quietly Winning Investor Trust
There are also growing concerns about appetite for US debt, with some foreign investors and central banks showing signs of diversifying away from Treasuries. Central banks’ gold reserves exceeded US government bonds and euros, comprising 27% of total official foreign reserves by the end of 2025, surpassing the euro’s 15% and US Treasuries’ 22% share. This shift shows central banks are quietly rethinking where they park their money.
Bottomline
The bond market turmoil is not a one-off event but a build-up of several pressures acting together. The Iran war and blocked Strait of Hormuz have kept oil prices high, which in turn is keeping inflation sticky and limiting the Fed’s room to cut rates.
At the same time, widening US fiscal deficit and rising debt-servicing costs are making investors demand higher compensation for holding US government debt.
Add to this the possibility of Japanese investors shifting back to higher-yielding domestic bonds, and central banks quietly favouring gold over Treasuries, and the picture becomes clear: global demand for US debt is no longer a given, even though they are considered a ‘risk-free’ security.
The yield on the 10-year US Treasury note decreased to 4.65% on Wednesday, having reached a peak of 4.75% in the prior session, following the Treasury’s announcement to double the size of buybacks on long-dated securities. Expect some more government intervention in order to reduce bond selling and stabilize yields over the medium term.
Disclaimer: This article is for informational purposes only and should not be construed as investment advice. Bond yields, interest rates, and fiscal data are subject to change, and past trends do not guarantee future outcomes. Readers should consult a qualified financial advisor before making any investment decisions based on this information.