



India’s residential property market continues to absorb housing supply at a steady pace in August, with sales across the top seven cities rising despite a high base. Axis Capital said the recent run of project launches is now translating into sustained bookings, while rising property prices are lifting the value of sales without a sharp build-up in inventory.
A recent report by Axis Capital stated that the the market’s recent performance has been supported by consistently high launches since December 2025. Hyderabad and Mumbai Metropolitan Region performed well during August, while National Capital Region and Bengaluru remained relatively stable.
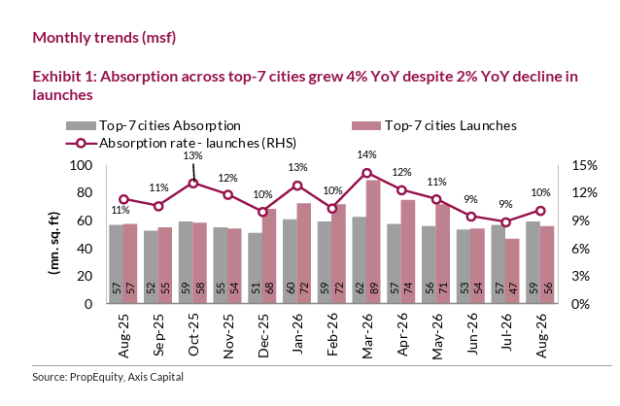
Across the top seven cities, absorption increased 4% year-on-year to 59.4 million sq ft in August. Sustenance bookings accounted for 90% of total bookings, while average realisation increased 8% year-on-year to Rs 11,503 per sq ft, taking the value of sales across the seven markets up 13% to Rs 68,300 crore.
Axis Capital on Prestige Estates Projects: ‘Buy’
Axis Capital has set a target price of Rs 2,060 for Prestige Estates Projects, implying 40% upside.
Prestige Estates Projects is one of Axis Capital’s four unchanged top picks in the residential property sector. The brokerage’s view comes as housing absorption remains steady across the major markets, with sustenance bookings accounting for the bulk of August sales.
Axis Capital said, “Top-7 cities recorded an absorption of 59.4msf, up 4% YoY, despite a high base. The outcome is better than the average of ~58msf seen since Jan-26, which is when the run-rate started seeing an uptick.”
The brokerage said the improvement has been supported by consistently high launches since December 2025, which are now translating into better sustenance sales. New-launch absorption declined 12% year-on-year in August, while sustenance bookings increased 6% to 53.7 million sq ft.
Axis Capital also expects consolidation in the housing market to continue in favour of branded and listed developers. Its four top picks are Prestige Estates Projects, DLF, Brigade Enterprises and Max Estates.
Axis Capital on DLF: ‘Buy’
Axis Capital has set a target price of Rs 1,000 for DLF, implying 49% upside from current levels.
DLF’s coverage comes against a softer August for the National Capital Region, where lower launches limited the supply of new projects. Launches in the National Capital Region fell 42% year-on-year to 4 million sq ft, compared with an average of 9 million sq ft over the previous 12 months.
Axis Capital said, “NCR continued to be impacted by lower launches, with absorption falling 4% YoY and 12% below the LTM average to 6.6msf. Bengaluru was soft despite higher launches, down 5% YoY but in line with the LTM average.”
Despite the weaker launch activity, the National Capital Region continued to have one of the lowest inventory overhangs among the major cities. The August overhang was around 15 months, while inventory stood at 49,000 units.
Axis Capital’s assessment of the wider market also points to stable inventory as a factor supporting continued price growth. Across the top seven cities, inventory stood at 634,000 units and overhang remained around 17 months in August.
Axis Capital on Brigade Enterprises: ‘Buy’
Axis Capital has set a target price of Rs 890 for Brigade Enterprises, implying 47% upside.
Brigade Enterprises is among the four stocks that Axis Capital has retained as its top picks. The brokerage’s assessment comes as Bengaluru continues to maintain a relatively high launch run-rate even though August absorption was softer year-on-year.
Axis Capital said, “Bengaluru was soft despite higher launches, down 5% YoY but in line with the LTM average. Pune was flat at 10.7msf despite lower launches.”
Bengaluru recorded launches of 12 million sq ft in August, up 18% year-on-year. The city absorbed 10.4 million sq ft during the month, with absorption remaining broadly in line with its long-term average.
Inventory in Bengaluru stood at 157,000 units in August, while the overhang was around 16 months. Axis Capital’s data also shows that the city’s launch activity has remained elevated through much of the past year.
Axis Capital on Max Estates: ‘Buy’
Axis Capital has set a target price of Rs 800 for Max Estates, implying 30% upside from current levels.
Max Estates is the fourth top pick retained by Axis Capital as the brokerage expects housing demand to remain consistent provided project launches continue and property prices maintain a steady upward trend.
Axis Capital said, “We expect demand to remain consistent going forward so long as launches support and prices see a steady uptick. We also see consolidation continuing in favor of branded/listed developers.”
The brokerage’s August assessment showed top-seven city launches at 55.8 million sq ft, down 2% year-on-year but up 20% month-on-month. Although launches were below the January-August average of 66.9 million sq ft, the recent supply run-rate has supported sustained bookings.
Max Estates Limited sits within the listed developer segment that Axis Capital expects to benefit from continued consolidation. The brokerage has retained Prestige Estates Projects Limited, DLF Limited, Brigade Enterprises Limited and Max Estates Limited as its four top picks.
Hyderabad and Mumbai Metropolitan Region lead absorption
The city-level data shows a wide difference in performance across India’s major residential markets. Hyderabad absorbed 13 million sq ft in August, up 19% year-on-year and 18% above its long-term average, while Mumbai Metropolitan Region recorded bookings of 15.4 million sq ft, up 13% year-on-year.
Axis Capital said, “Hyderabad posted a surge in launch run-rate over the last 12 months, with the average coming in at 15msf, vs 10.5msf in the previous 12 months. Consequently, absorption run-rate also improved meaningfully.”
Mumbai Metropolitan Region has also seen its launch run-rate improve since the unwinding of the environmental clearance issue in October 2025. The higher supply has translated into stronger absorption, with August bookings 8% above the region’s long-term average.
| City | August absorption | Year-on-year movement | August launch trend |
| Hyderabad | 13.0 million sq ft | +19% | +30% |
| Mumbai Metropolitan Region | 15.4 million sq ft | +13% | Stable year-on-year |
| National Capital Region | 6.6 million sq ft | -4% | -42% |
| Bengaluru | 10.4 million sq ft | -5% | +18% |
| Pune | 10.7 million sq ft | Flat | -16% versus the last 12-month average |
Prices rise while inventory remains controlled
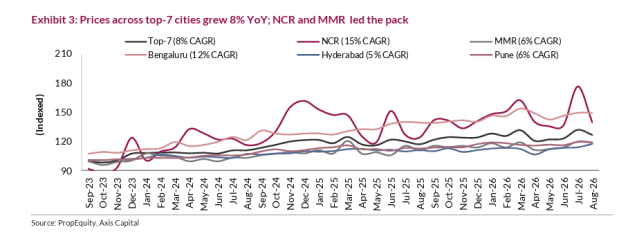
Average realisation across the top seven cities increased 8% year-on-year to Rs 11,503 per sq ft in August. National Capital Region recorded the strongest price growth among the major markets at 13% year-on-year.
The combination of higher prices and increased absorption lifted the value of sales across the top seven cities by 13% year-on-year to Rs 68,300 crore.
Axis Capital said, “Inventory was stable at 634k units with overhang comfortable at 17 months.”
The report’s monthly data also shows that inventory declined month-on-month in August after rising through the first half of 2026. The seven-city inventory level stood at 635,000 units on the unit-based measure, with overhang at 17.2 months.
Sustenance bookings account for most sales
The composition of August absorption is an important part of Axis Capital’s assessment. New-launch absorption declined 12% year-on-year, with the absorption rate falling 113 basis points to 10%.
Sustenance bookings increased 6% year-on-year to 53.7 million sq ft and accounted for 90% of total bookings. Axis Capital attributed this performance to the scale-up in launches since December 2025.
The report said, “Against flattish launches during the month, absorption volume saw a steady 4% YoY growth to 59.4msf, largely led by sustenance bookings, which were supported by strong scale-up in launches since Dec’25.”
The distinction between new-launch and sustenance sales is important in understanding the August numbers. While fewer sales came from newly launched projects, existing projects continued to generate bookings at a healthy pace.
Launch activity remains important for demand
Top-seven city launches stood at 55.8 million sq ft in August, compared with a January-August average of 66.9 million sq ft. Launches increased 20% month-on-month but declined 2% year-on-year.
Hyderabad was the strongest market on the supply side, with August launches increasing 30% year-on-year to 18.8 million sq ft. Bengaluru also maintained a strong launch run-rate, with launches rising 18% year-on-year to 12 million sq ft.
National Capital Region remained the main weak market, with August launches at just 4 million sq ft against its 12-month average of 9 million sq ft. Pune also recorded launches below its recent average, while Mumbai Metropolitan Region reported 9.3 million sq ft of launches against a 12-month average of 14 million sq ft.
Conclusion
Axis Capital’s real estate sector report retains four top picks while pointing to steady absorption, rising prices and controlled inventory across the leading residential markets. The brokerage expects demand to remain consistent as long as developers continue to bring projects to market and pricing maintains its current upward direction.
Disclaimer: This article is based solely on the Axis Capital India Real Estate update, provided for this story. The ratings, target prices, upside estimates, housing-market data, forecasts and analytical views attributed to Axis Capital, Pritesh Sheth and Rishith Shah are those contained in the report and have not been independently verified by the publication. The upside percentages are those stated by Axis Capital and can change with market prices. The housing-market data cited in the report is sourced primarily from PropEquity and Bloomberg, as identified by Axis Capital. Actual sales, launches, prices, inventory, project execution, financial performance and market conditions may differ from the assumptions contained in the report. This article is intended for informational purposes only and should not be construed as investment advice or a recommendation to buy or sell any security.