



Indian IT services companies could face subdued growth for another year as demand remains uneven and the impact of AI-driven pricing pressure becomes a bigger part of the sector debate, according to Citi Research. The brokerage expects only modest sequential growth for the leading companies in the September quarter and says there are still few signs of a broad-based recovery.
According to the Citi Research analyst, the sector is heading towards a fourth consecutive subdued growth year, with demand weakness persisting despite the seasonally stronger second quarter. “Investor sentiment appears mixed – debates on what the eventual outcome of deflation in existing businesses and acceleration in new work imply for overall sector growth,” Goyal wrote.
The report also points to limited room for near-term optimism, with management commentary on growth recovery, AI-led deflation, new AI opportunities and margins set to be key areas to watch during the upcoming earnings season.
Citi expects mixed demand across IT services
Citi’s discussions with IT services companies suggest that demand remains uneven across industries. BFSI continues to be the strongest vertical, while healthcare, manufacturing, telecom and energy spending remains mixed.
“No company pointed to a broad-based recovery,” Citi said in its sector assessment.
The brokerage also sees AI becoming an increasingly important differentiator. Companies are discussing domain expertise, client relationships and AI execution capabilities as they compete for new work, while modernisation, sovereign AI and industry-specific AI solutions are opening opportunities beyond traditional services.
At the same time, Citi said productivity gains and changing pricing models have so far helped companies absorb some of the pressure from AI-related deflation.
Citi’s IT targets: Infosys and Mphasis may see limited upside
Citi’s valuation table, based on prices at the September 25 close, shows target prices below the prevailing prices for most of its Indian IT coverage. Infosys and Mphasis are the two exceptions, with target prices of Rs 1,030 and Rs 2,400 respectively.
| Company | Citi target price | Implied upside/downside |
| Tata Consultancy Services | Rs 1,875 | -10.0% |
| Infosys | Rs 1,030 | 2.9% |
| Wipro | Rs 140 | -14.6% |
| HCL Technologies | Rs 1,030 | -18.2% |
| Tech Mahindra | Rs 1,350 | -12.7% |
| Persistent Systems | Rs 4,650 | -13.6% |
| LTIMindtree | Rs 3,620 | -11.3% |
| Mphasis | Rs 2,400 | 5.7% |
| Coforge | Rs 1,670 | -6.4% |
| Hexaware Technologies | Rs 465 | -6.4% |
| LTTS | Rs 3,115 | -2.8% |
The implied percentages are calculated from the current-price and target-price figures in Citi’s valuation table, which the report says are based on the September 25, 2026 close. The calculations are not live market-price comparisons.
TCS, Infosys and HCLTech: Citi keeps growth expectations modest
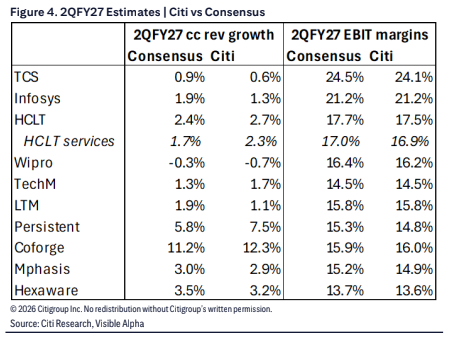
For FY27, Citi expects constant-currency revenue growth of 2.6% for TCS, 1.5% for Infosys and 3.1% for HCLTechnologies.
The brokerage’s estimates are below consensus for Tata Consultancy Services Ltd. and Infosys Ltd. but slightly above consensus for HCL Technologies. For FY28, Citi expects revenue growth of 1.5% for TCS, 1.8% for Infosys and 3.4% for HCL Technologies.
| Company | Citi FY27 revenue estimates | Consensus | Citi FY28 revenue estimates | Consensus |
| TCS | 2.6% | 3.4% | 1.5% | 3.1% |
| Infosys | 1.5% | 2.0% | 1.8% | 2.9% |
| HCL Technologies | 3.1% | 3.0% | 3.4% | 4.9% |
| Wipro | -0.7% | -0.1% | 1.0% | 1.8% |
| Tech Mahindra | 6.4% | 6.3% | 2.6% | 4.3% |
| LTIMindtree | 5.2% | 6.2% | 5.2% | 7.5% |
Citi also expects FY27 EBIT margins of 24.2% for TCS, 20.9% for Infosys and 17.3% for HCL Technologies. For Wipro, Tech Mahindra and LTIMindtree, its margin estimates are 16.3%, 14.8% and 15.7% respectively.
Wipro and LTIMindtree face a slower growth outlook
Citi expects Wipro’s FY27 constant-currency revenue to decline 0.7%, compared with a 0.1% decline in consensus estimates. For FY28, the brokerage sees only 1% growth against 1.8% expected by consensus.
For LTIMindtree, Citi’s FY27 growth estimate of 5.2% is below the 6.2% consensus expectation. Its FY28 estimate of 5.2% is also below the 7.5% consensus forecast.
The brokerage expects Tech Mahindra to grow 6.4% in FY27, slightly above the 6.3% consensus estimate, although its FY28 forecast of 2.6% is well below the 4.3% consensus estimate.
AI is moving beyond productivity tools
Citi’s notes from its global TMT conference point to a broader change in how enterprises are approaching AI adoption.
“Context is key. Proprietary workflows, process data and enterprise knowledge are becoming more valuable than model access,” Citi said.
The brokerage also said AI returns are highest when companies automate end-to-end business processes rather than isolated tasks. Adoption remains relatively early, with data, governance, security and legacy systems continuing to constrain the pace of deployment.
Citi expects AI to develop from a productivity tool into a driver of revenue, innovation and broader technology spending, although the transition could also create pricing pressure in existing services businesses.
What Citi wants to hear from companies
For the upcoming earnings season, Citi is watching management commentary on growth, margins, deal activity and AI-related pricing pressure.
For TCS, the focus areas include BFSI, manufacturing and high-tech demand, along with any update to its margin outlook. For Infosys, Citi expects attention on revenue guidance, while HCL Technologies is expected to provide an update on revenue guidance and margins.
For Wipro, the brokerage is watching third-quarter guidance and margin commentary. Tech Mahindra’s ability to reach its 15% FY27 margin objective is another focus area.
Citi is also watching LTIMindtree’s revenue growth and top-client outlook, Coforge’s FY27 revenue outlook excluding Encora and the latter’s outlook, while Persistent Systems’ growth trajectory, margin performance and high-tech vertical are among the key points to track.
IT sector: Deal activity may not tell the whole story
Citi expects deal TCV trends to remain mixed and cautions that the relationship between deal wins and near-term revenue growth remains limited.
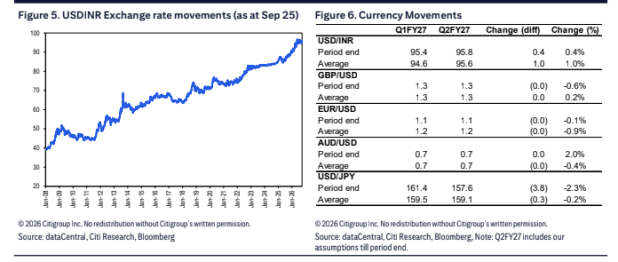
The brokerage also expects currency support to be less helpful for margins than it has been in recent quarters. With the rupee’s recent tailwind limited, the management commentary on margin performance will be important in the next set of results.
Disclaimer: This article is based solely on the Citi Research report provided. The target prices, estimates, business outlook, sector views and other analytical comments attributed to Citi Research and its analyst are their own and have not been independently verified by the publication. The upside and downside percentages are calculated from the current-price and target-price figures stated in the report and do not represent live market prices. Actual financial and operating results may differ from brokerage estimates because of business conditions, demand, execution, currency movements, pricing, competition, AI adoption, regulatory developments and broader market factors. This article is intended for informational purposes only and should not be construed as investment advice or a recommendation to buy or sell any security.