



Antibody-drug conjugates, or ADCs, are becoming an increasingly important part of the global drug-development pipeline, and the manufacturing opportunity around them is drawing Indian CDMO companies deeper into a specialised and potentially high-value segment. Piramal Pharma, Anthem Biosciences and Cohance Lifesciences are among the listed Indian names with disclosed ADC-related capabilities, programmes and investments, giving them different routes into a market that requires expertise across potent payloads, linkers, conjugation, biologics and drug-product manufacturing.
Identifying the ADC opportunity within CDMO business
The three companies, however, are taking very different bets. Piramal Pharma is building an integrated ADC manufacturing offering while adding biologics capabilities through Yapan Bio; Anthem has ADC programmes within a large CRDMO business; and Cohance is developing ADC payloads and linkers alongside drug-product capabilities through NJ Bio. Their capacity plans, customer programmes, order visibility and financial performance also differ sharply.
That sets up a more interesting question than simply asking which companies have an ADC connection: how much of the ADC manufacturing opportunity has each company captured, where are they positioned in the value chain, and which one has the strongest combination of capacity, customer programmes, CDMO economics and financial performance?
Why ADC CDMO is a high-margin opportunity for pharma companies
ADC manufacturing sits within the broader CRDMO business, where specialised work can carry materially higher margins than other pharma activities. Jefferies’ August 25, 2026 India CRDMO review said the “CRDMO segment typically is a higher-margin business while other divisions are lower-margin businesses”, with the final company margin depending on business mix.
Across the nine CRDMO companies covered by Jefferies, CRDMO revenue grew 19% YoY in Q1 FY27, the strongest growth rate in seven quarters, while aggregate EBITDA grew 36%. Jefferies also recorded a 308-basis-point YoY improvement in Piramal Pharma’s EBITDA margin.
The relevance to ADCs comes from the number of specialised manufacturing steps involved. Payload and linker chemistry, conjugation, biologics manufacturing and drug-product work can sit within the same development programme. A CDMO with capabilities across several of those steps can potentially retain more work as a molecule moves through development and towards commercial supply.
Piramal Pharma, Anthem Biosciences and Cohance Lifesciences are approaching that opportunity from different parts of the chain.
Piramal Pharma: Building an integrated ADC manufacturing platform
Piramal Pharma is putting together an ADC offering that spans payload-linker manufacturing, conjugation and sterile drug-product manufacturing, while the Yapan Bio acquisition adds biologics capability.
Its ADCelerate platform includes conjugation at Grangemouth in the UK. The company has added commercial-scale payload-linker development and manufacturing at Riverview in Michigan, while Lexington in Kentucky is being expanded for sterile injectable manufacturing. The Riverview and Lexington projects form part of a $90 million expansion programme.
Peter DeYoung, CEO, Global Pharma, Piramal Pharma said during the con call presentation, “We continue to expect the conjugation to be the anchor and the largest contributor to our offering, where we think we have the most differentiation.”
The newer Riverview payload-linker capability is already seeing customer interest. Management said the existing capacity was effectively sold out and that the additional room required an investment of less than $5 million.
Lexington adds commercial sterile manufacturing to the same broader offering. Piramal’s FY27 capex guidance is $120 million-$135 million, with around $21 million spent in Q1.
The company has also partnered with Ajinomoto Bio-Pharma Services around AJICAP site-specific conjugation technology, combining the technology with Piramal’s manufacturing capabilities.
Yapan Bio gives the group another entry point into biologics. Piramal acquired an additional 40.67% stake for Rs 76.09 crore, taking its holding to 74%. Yapan brings biologics, biotherapeutics and vaccine capabilities, including process development and GMP manufacturing.
Piramal’s CDMO operation is also generating strong activity outside the ADC programme. Management has described its FY27 order book as stronger than in the past several years, while Jefferies reported healthy order inflow across sites. RFP activity has increased across most CDMO locations, with a significant portion directed towards overseas facilities. Customer decision timelines remain extended, however, leaving conversion of the RFP pipeline into actual orders as an important next step.
The company’s strategy is consequently not built around a single ADC manufacturing step. It is trying to bring several pieces together so that a customer can use Piramal for payload-linker work, conjugation and drug-product manufacturing, with biologics capability now sitting alongside that offering.
Piramal Pharma share price performance
Anthem Biosciences: ADC programmes inside a CRDMO-heavy business
Anthem comes into ADCs from a different starting point because CRDMO is already the centre of its business.
The company has more than 100 early-stage programmes and 10 late-phase molecules, with ADC molecules included among the late-stage programmes. Management has said some of these programmes can take another 18-24 months to reach commercialisation, depending on their progress.
Ajay Bhardwaj, Managing Director and Chief Executive Officer, Anthem Biosciences said during the earnings call, “It gives us a foot in. We’ve seen in the past, that’s a nice way to get into a company.”
That comment captures the importance of Anthem’s development pipeline. ADC exposure does not have to begin with a commercial manufacturing contract. A programme can enter through development work and potentially expand as the molecule advances.
Anthem’s customer pipeline also has a more immediate order component. Management said 60% of what the company needed to execute was already covered by its order book. Jefferies separately reported 80%+ order-book visibility against FY27 target CRDMO sales. The two figures use different bases and are therefore best retained with their respective attribution.
The Q1 revenue decline was linked by management to customer delivery timing. Customers deferred deliveries from Q1 into Q2, Q3 and Q4, leaving a heavier shipment schedule for the remaining quarters.
Anthem has also added a new Big Pharma customer. Management said the relationship should contribute meaningful business later, with the engagement covering R&D, new projects and products that the customer wants to source for supply-chain diversification.
Capacity is being added alongside this programme pipeline. Unit 2 was operating at around 50% utilisation, while Unit 3 was at around 30%-35%. Unit 4 is being developed with 365 kilolitres of custom-synthesis capacity and 100 kilolitres of fermentation capacity.
For Anthem, therefore, ADC exposure sits inside an established CRDMO model where development programmes, customer relationships, manufacturing capacity and order coverage can feed into one another.
Anthem Biosciences share price performance
Cohance Lifesciences: Building ADC payload and linker capabilities
Cohance is taking a more specialised route into ADCs, with work spanning payloads, tailored linkers, bioconjugation and drug-product manufacturing.
The company’s payload programme includes MMAE and Exatecan, with management reporting customer interest from companies seeking alternatives to Chinese suppliers.
Cohance has filed one new ADC payload DMF, while three additional payload filings are progressing. Its US-based cGMP expansion involves $10 million and is intended to support ADC supply up to Phase 2b by FY27.
The company has completed GMP bioconjugation batches and delivered an end-to-end ADC product for a clinical-stage programme. NJ Bio adds drug-product manufacturing capability, including another GMP ADC batch during Q1 and an additional GMP manufacturing laboratory at Princeton supporting small-molecule and biologic programmes through Phase 1 and Phase 2 development.
The next ADC-specific programme milestone is scheduled for Q2 FY27.
Umang Vohra, Executive Chairman and Group CEO, Cohance Lifesciences said during the earnings call announcemnet, “The customized ADC payload order remains on schedule for delivery in Q2FY27.”
Cohance has not disclosed an annual order-book percentage comparable with Anthem’s disclosure. Instead, management has pointed to scheduled commercial programme deliveries, restocking orders, customer qualifications and new programme awards as sources of growth through FY27.
The company’s broader operating recovery is important to the ADC story because the specialised business is being developed while the wider CDMO operation is under pressure. Management expects Q2 to improve and YoY growth to return in H2 FY27.
That makes the Q2 payload delivery particularly useful as a tangible test of how the ADC programme pipeline is progressing.
Cohance Lifesciences share price performance
Piramal Pharma vs Anthem Biosciences vs Cohance: ADC exposure and financial comparison
| Parameter | Piramal Pharma | Anthem Biosciences | Cohance Lifesciences |
| ADC exposure | Payload-linker, conjugation, sterile injectables, biologics | ADC programmes within CRDMO | Payloads, linkers, bioconjugation, ADC drug products |
| Q1 FY27 revenue | Rs 2,269.92 crore | Rs 418.22 crore | Rs 422.26 crore |
| Q1 revenue growth (YoY) | 17% | -22.6% | -23.1% |
| CDMO revenue | Rs 1,187 crore | Rs 341 crore | 38% of revenue |
| CDMO share | 52% | 81.5% | 38% |
| EBITDA margin | 12.5% consolidated | 39.6% | 2.2% adjusted |
| Q1 PAT | -Rs 69 crore | Rs 119.94 crore | -Rs 45.19 crore |
Sources: Company Q1 FY27 data and Jefferies India CRDMO Performance Review
The operating profiles are markedly different. Piramal’s ADC strategy is being built on top of a sizeable CDMO operation, while Anthem’s CRDMO business already forms the bulk of the company. Cohance has specialised ADC capabilities but is developing them while working through a weaker quarter for the broader business.
Jefferies’ comparison also places the three at very different points on capital efficiency, with FY26 ROCE at 25% for Anthem and 1% for Piramal, while Cohance is shown as NA.
The valuation table shows a sizeable difference in how the market is pricing the three businesses. Anthem’s multiple sits below Cohance’s on both P/E and EV/EBITDA, while Piramal’s negative earnings make its P/E unsuitable for a conventional comparison.
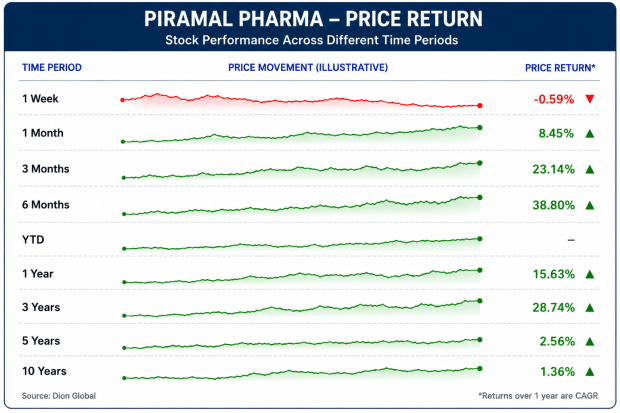
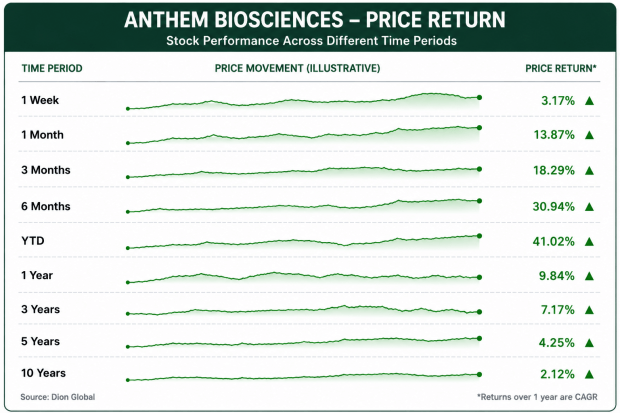
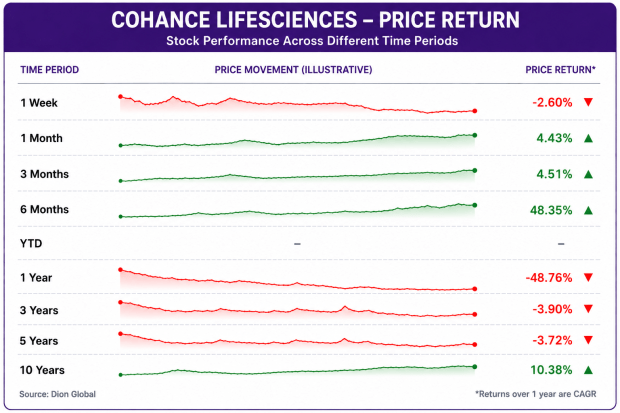
The return profile is also not uniform. Anthem’s recent performance has been stronger over the shorter periods shown in the table, Piramal has delivered positive returns across the one-year and three-year periods, while Cohance’s longer-term record remains weighed down by the sharp fall over the past year.
What the ADC pipeline means for each company’s next phase
Piramal’s next stage is about making its integrated offering work as a commercial proposition. Riverview adds payload-linker capacity, Grangemouth provides conjugation and Lexington is being expanded for sterile drug-product manufacturing. Yapan adds another biologics capability. The company therefore has several points from which it can pursue a single customer relationship.
Anthem’s opportunity comes through its existing CRDMO network. The company already has a large development pipeline and order coverage, while customer deliveries deferred from Q1 are expected across the remaining quarters. Its ADC programmes can therefore progress within a business that already has established customer engagement and manufacturing infrastructure.
Cohance has a more focused ADC proposition around payloads and linkers, with bioconjugation and NJ Bio drug-product capabilities extending its reach. Its immediate ADC delivery gives the market a tangible programme milestone to track, while management is simultaneously targeting a recovery in the broader CDMO business.
The distinction is important when reading the ADC story. Piramal is trying to build more of the chain, Anthem is trying to move ADC programmes through an existing CRDMO engine, and Cohance is trying to deepen specialised ADC capabilities while rebuilding its broader operating base.
Piramal Pharma, Anthem Biosciences and Cohance: PE ratio and more
| Stock metric | Piramal Pharma | Anthem Biosciences | Cohance Lifesciences |
| Share price, Aug 31, 2026 | Rs 215.20 | Rs 903.10 | Rs 452.10 |
| Market capitalisation | Rs 28,379 crore | Rs 50,380 crore | Rs 17,016 crore |
| 52-week low | Rs 132.50 | Rs 579.45 | Rs 267.85 |
| 52-week high | Rs 220.40 | Rs 942.00 | Rs 1,038.00 |
| TTM EPS | -Rs 2.36 | Rs 10.23 | Rs 2.78 |
| P/E | -90.25x | 87.68x | 162.56x |
| P/B | 3.50x | 16.00x | 4.47x |
| EV/EBITDA | 19.72x | 37.03x | 25.56x |
Source: NSE and Financial Express market dataTicker
Conclusion: Three ADC bets, one test
The ADC opportunity within the CDMO business is moving from capacity building to customer conversion, and that is where the three companies should begin to separate.
Piramal, Anthem and Cohance have different ways of reaching the same market, with different levels of integration, programme maturity and existing customer exposure.
The next few quarters will show which capabilities translate into repeat programmes and commercial manufacturing.
Disclaimer: This article is based on publicly available information, including company filings, management commentary, earnings-call transcripts, market data and research reports cited in the copy. The views and analysis presented are for informational and educational purposes only and should not be construed as investment advice, a recommendation, solicitation or an offer to buy or sell any securities. Readers are advised to consult a SEBI-registered investment adviser and conduct their own independent research before making any investment decisions. Past performance is not indicative of future returns. Market prices, valuations, financial results and business prospects may change. The publication and the author do not assume responsibility for any investment decisions or losses arising from the use of the information contained in this article.