



Three companies. Three different businesses. The global brokerage house Jefferies has given a ‘Buy’ rating to three large-cap stocks. According to the brokerage report, ONGC, PB Fintech and Bharti Airtel could deliver an upside potential of up to 30% from current levels.
Let’s take a look at the key reasons why the brokerage house is bullish on this stock –
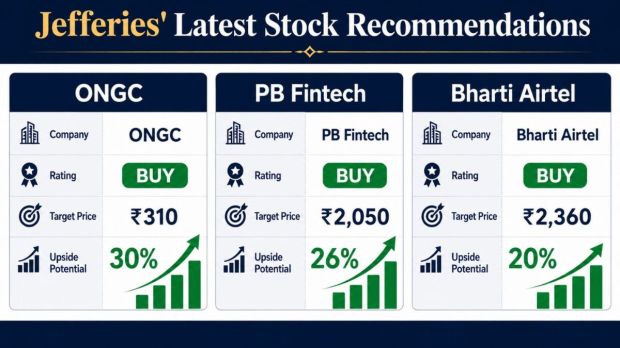
ONGC: Better earnings, but production remains a concern
Oil and Natural Gas Corporation (ONGC) delivered quarterly earnings that were ahead of expectations, as per the brokerage house report. The improvement was supported by lower losses at Hindustan Petroleum Corporation (HPCL) and lower exploration costs.
However, the brokerage noted that crude oil and natural gas production remained weaker than expected.
Jefferies said, “Consolidated EBITDA/PAT was above Jefferies estimates on lower than expected HPCL losses. Production failed to cheer.”
The brokerage also highlighted that the absence of any government cap on crude oil prices and a higher share of market-linked gas sales remain positive for earnings.
At the same time, production from the Krishna-Godavari (KG) basin continues to be a concern. “KG production has declined from the recent peak of 35kbpd crude/3.2 mmscmd to 21kbpd/1.5mmscmd due to reservoir complexity issues,” the report said.
Despite trimming production estimates for the next two financial years, Jefferies maintained its positive view, adding, “Production growth could drive re-rating.”
Jefferies on PB Fintech: Revenue growth improves despite higher expenses
PB Fintech, the parent company of Policybazaar, reported strong revenue growth during the June quarter. According to the Jefferies report, premium growth remained healthy, while insurance policy renewals continued to improve.
However, profitability fell slightly short of expectations because advertising and other operating expenses increased faster than anticipated.
Jefferies in its report noted that the policy renewals are expected to remain strong over the coming year, while businesses outside Policybazaar are also expanding steadily.
Jefferies said, “Growth momentum expected to sustain.” It also noted that “The businesses outside Policybazaar also gained traction.”
The brokerage has slightly raised its earnings estimates for the coming years and continues to expect steady growth from both its insurance and financial services businesses.
Jefferies on Bharti Airtel: Subscriber growth remains the key support
Bharti Airtel also delivered a mixed quarter. Revenue and operating profit were better than expected, although adjusted profit came in below estimates because of higher depreciation, finance costs and taxes.
Jefferies believes the telecom operator remains on a solid growth path.
The brokerage said, “Higher than expected mobile subscribers and ARPU, strong growth in Airtel business & Africa and healthy FCF generation were the key positive surprises in Q1 results.”
Average Revenue Per User (ARPU) continued to improve, while subscriber additions remained healthy.
The brokerage also expects strong cash generation to support future growth. “Strong FCF generation bode well for payouts,” Jefferies said.
Furthermore, the brokerage house also noted that the company is expected to benefit from continued mobile business growth and a possible tariff hike in the future.
What investors need to watch
While near-term concerns remain for all three companies, Jefferies believes these are outweighed by their long-term growth prospects. According to the brokerage report, improving earnings, stronger business fundamentals and future growth triggers continue to support its ‘Buy’ ratings.
Disclaimer: The investment views, target prices, and stock recommendations expressed in this article belong solely to the reporting brokerage house and do not constitute financial advice or an offer or solicitation to buy or sell securities. Financial Express does not endorse or guarantee the accuracy of market predictions or upside claims. Equity markets involve substantial risk of loss, and past performance or analyst projections are no guarantee of future results. Readers should perform their own due diligence and consult a SEBI-registered financial advisor before making any investment decisions. This disclaimer has been generated using AI to support user well-being and responsible content consumption.