



For Indians moving abroad, the focus before departure is usually on getting the visa, securing a job or university admission, finding accommodation and booking a flight. But becoming an NRI can change how their money is managed in India – from bank accounts and investments to taxes, loans and insurance.
The financial mistakes often begin before the flight. An account that should have been redesignated, an investment left unchecked or an EMI without a repayment plan can become harder to sort out after moving abroad.
Financial Express Digital spoke to Amit Gupta, Founder at eazyPetition, and Suresh Rajan, Founder & Executive Chairman, LCR Capital Partners, about the financial mistakes Indians should avoid before relocating abroad. Both experts spoke about the importance of putting the India-side financial position in order before departure.
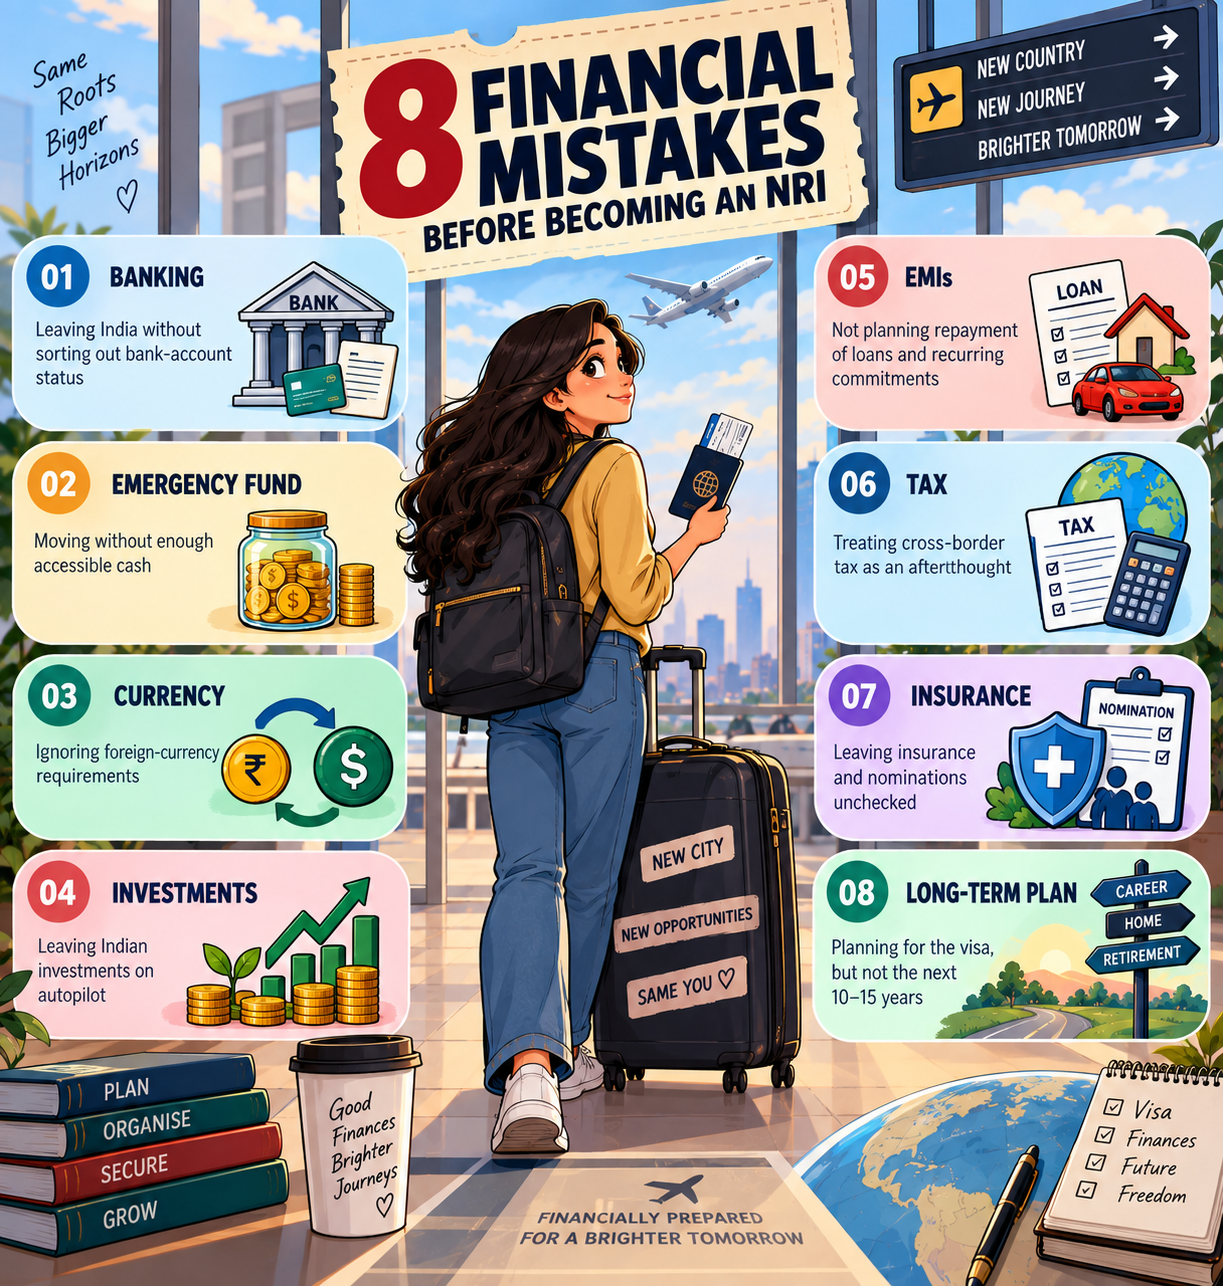
Here are eight mistakes Indians should fix before they become NRIs:
1. Leaving India without sorting out your banking status
One of the first things an Indian moving abroad should review is the status of their bank accounts. Gupta says one of the most common mistakes is leaving India without converting a resident savings account to an NRO account, where required, and completing the necessary KYC updates.
Once a person’s residential status changes, their banking arrangements need to reflect that change. Completing the process while still in India can be easier than trying to do it after moving abroad, when additional documentation, notarisation, apostille or consular authentication may be required in some cases.
“The most common mistake is not converting their resident savings account to an NRO account and completing the required KYC updates before leaving India,” Gupta says.
An NRO account is generally used by NRIs to manage income earned or assets held in India, while an NRE account is primarily used to hold overseas earnings in India. NRE funds are generally repatriable, while NRO accounts are subject to different repatriation rules and limits.
Rajan says this should not be treated as routine paperwork that can be dealt with during the next visit to India.
“Your bank accounts, your investment accounts and the records your institutions hold on you are all built around the assumption that you live in India. Once that stops being true, they need to be brought into line,” he says.
The choice between NRO and NRE will depend on the nature and source of funds and how the NRI plans to use them. Individuals should check the applicable banking, FEMA and tax rules before restructuring their accounts.
2. Moving abroad without enough emergency money
The first few months after relocation can put considerable pressure on finances, with housing deposits, rent, transportation, healthcare, tuition and other settling-in costs adding up quickly.
Gupta recommends keeping an emergency fund equivalent to around six months of essential expenses accessible in the destination country.
The money should be liquid and easily accessible rather than locked into long-term investments. He also recommends arranging access to these funds before leaving India and keeping an international card as a backup for immediate expenses.
Rajan similarly recommends building a six-month cushion before departure. In the context of an India-to-US move, he advises having six months of US living expenses held in dollars before getting on the plane.
For other destinations, the amount and currency required will depend on the cost of living and the individual’s circumstances.
3. Ignoring currency planning
Moving abroad means earning and spending in a different currency, making liquidity and currency exposure important parts of the pre-departure plan.
Gupta advises individuals to review their liquid investments and cash holdings and assess how much they are likely to need in the destination country.
For students, this is particularly important because tuition, accommodation and living expenses may need to be paid in foreign currency. Planning these requirements in advance can help avoid having to transfer money urgently after arrival.
The objective, however, should not be to move as much money as possible before leaving India. The amount should be based on actual financial needs, investment objectives, currency exposure and applicable regulations.
4. Leaving Indian investments on auto-pilot
Moving abroad does not necessarily mean selling all investments held in India. But experts say those investments should not simply be left unattended.
Bank accounts, fixed deposits, mutual funds, equities, property, PPF and other assets should be reviewed before departure.
An NRI cannot open a new PPF account. However, if the PPF account was opened while the individual was a resident Indian, the existing account can generally continue until its original maturity. It cannot be extended beyond maturity after the person becomes an NRI.
An NRI should also inform the bank or post office about the change in residential status and ensure the account and linked bank details are updated.
Gupta says the broader issue is that Indians should review their India-based investments before moving rather than making decisions after they have already become non-residents. The tax treatment of income from Indian investments can also need to be reviewed depending on the destination country and the individual’s circumstances.
Rajan says people often do not make an actively wrong investment decision. Instead, they simply leave old decisions running. “Long-standing investments keep running on autopilot, even when continuing to hold them in the US carries a tax and reporting burden that outweighs their earnings,” he says.
This does not mean every investment should be sold before relocation. The appropriate decision depends on the destination country’s tax rules, the nature of the asset and the individual’s long-term plans.
People with substantial investments should consider professional advice covering both Indian and destination-country tax implications before selling, transferring or restructuring assets.
5. Forgetting loans, EMIs, PF and other commitments
Moving abroad does not end financial obligations in India. Professionals should review outstanding loans, EMIs, fixed deposits, investments and provident fund-related matters before departure.
Rajan says these decisions are frequently overlooked because they do not necessarily come with an obvious deadline. “Beyond that, what we see is not people making bad decisions. It is people leaving decisions unmade,” he says.
That could mean leaving retirement balances untouched, failing to review property-related income and obligations, or not deciding how existing loans and EMIs will be serviced after moving abroad.
Before departure, every recurring payment should have a clear repayment mechanism. If someone in India will need to handle financial matters on the individual’s behalf, the necessary authorisation should also be arranged.
Rajan specifically recommends considering a power of attorney with someone trusted.
6. Treating cross-border tax as an afterthought
Becoming an NRI can create tax and reporting obligations in both India and the destination country.
The exact rules depend on factors including residential status, income, financial assets and the laws of the country where the individual moves.
Gupta says people relocating abroad with significant financial accounts or investments in India should seek advice from a qualified tax professional before relocating.
For someone moving to the US, for example, FBAR, FATCA and the India-US DTAA can involve specific requirements depending on the person’s circumstances.
For Indians moving elsewhere, the same principle applies: understand the destination country’s tax residency and foreign-asset reporting rules before the move rather than discovering them after the first tax filing.
7. Leaving insurance and nominations unchecked
Insurance and nominations can easily be overlooked during an international move.
An individual may have life insurance, health insurance or other financial protection in India, but the usefulness and administration of those policies may need to be reviewed after becoming an NRI.
Rajan says insurance cover and nominations are among the things people often leave unchecked when relocating. He also recommends ensuring that someone in India is authorised to act on the person’s behalf where necessary.
Healthcare planning is particularly important for those moving to countries where medical treatment can be significantly more expensive than in India.
Gupta recommends travel insurance before leaving India and appropriate health insurance after arrival for people moving to the US. The exact requirement will vary by destination and whether the person is moving as a student, employee or dependent.
8. Planning only for the move, not the next 10–15 years
Perhaps the biggest mistake is treating an international relocation as a logistical exercise rather than a long-term financial transition.
A person may plan around the visa duration, first job or university course without asking what their financial life should look like several years later.
Rajan says families can end up planning a permanent move “as though it were a temporary one”. “The visa has a length, so the plan quietly takes on the same length, and decisions that need a fifteen-year horizon end up being made on a three-year one,” he says.
His advice is to separate the immigration timeline from the financial timeline and ask where the family wants to be financially in 15 years.
That could mean deciding whether Indian assets should continue to form part of the family’s wealth, how retirement savings will be built, whether property in India should be retained and how long-term residency plans could affect financial decisions.
The important thing is not to let visa renewals or short-term relocation decisions determine a family’s long-term financial strategy.
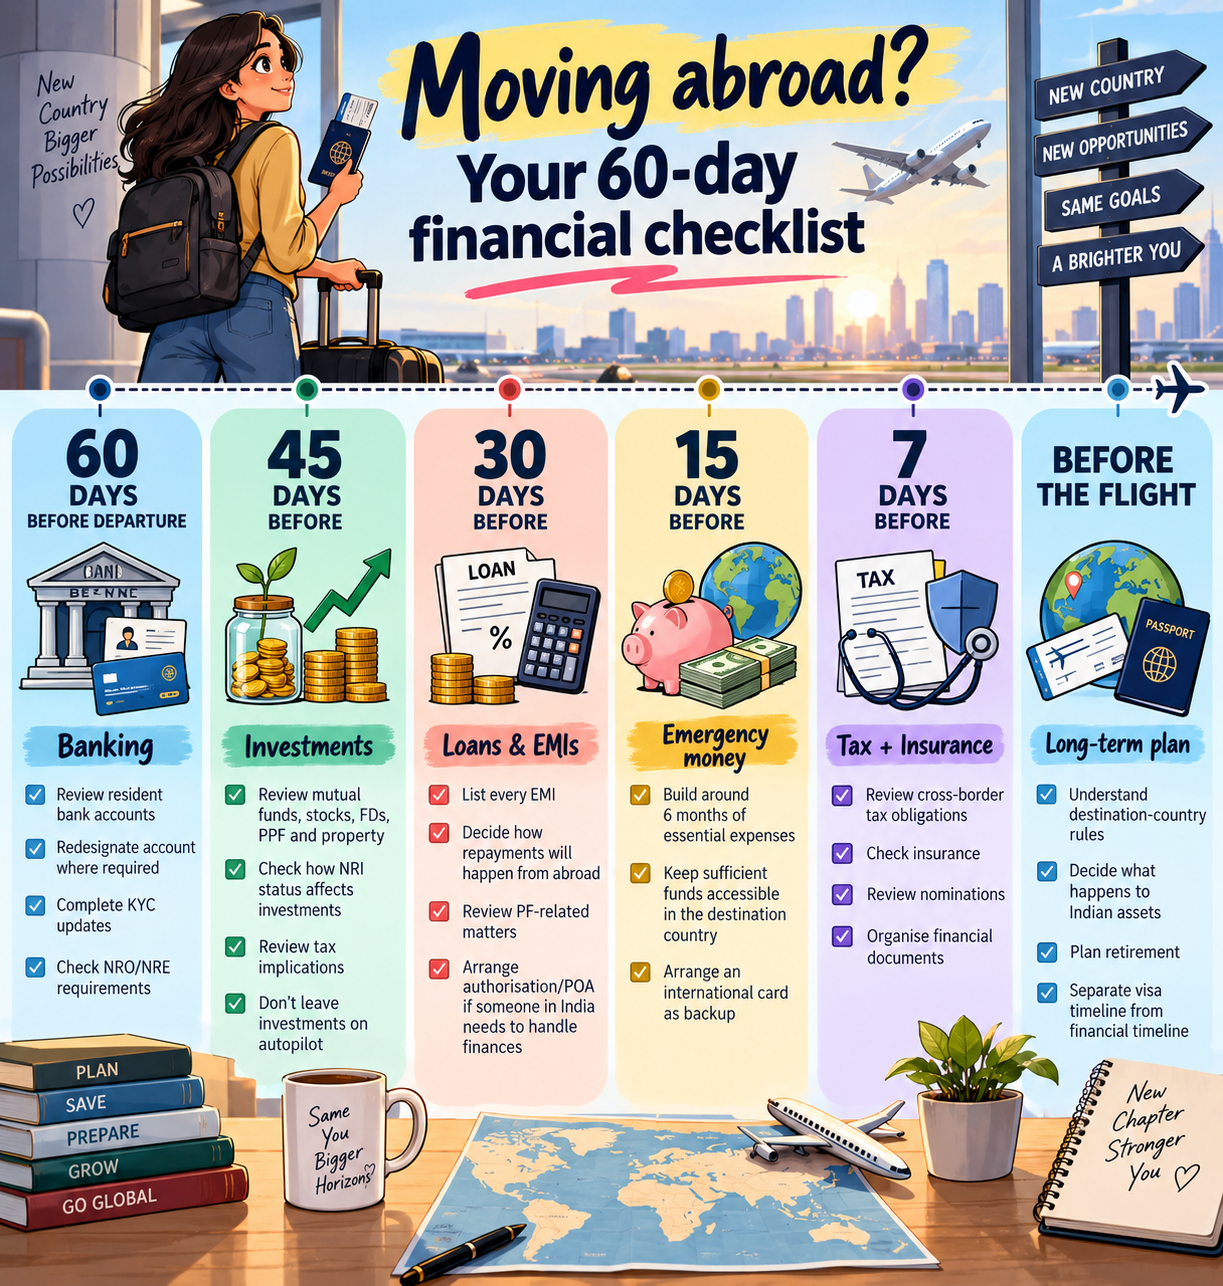
You have 60 days before leaving India. What should you do?
The final two months before departure can be used to tackle financial tasks that are easier to complete while still in India.
Gupta’s advice is to start with KYC and banking documentation as soon as travel is confirmed and the visa is stamped. This includes reviewing the bank account structure, organising financial documents, reviewing Indian investments and planning how much money will be required after arrival.
Rajan similarly recommends using those 60 days for transactions and administrative work that may become harder after the move.
His checklist includes redesignating accounts, resolving provident fund and SIP-related matters, putting a repayment mechanism behind every EMI and arranging a power of attorney where required. He also recommends building a six-month foreign-currency cushion before departure.
The destination matters because tax, banking, investment and insurance rules vary between countries. But the broader principle is the same – sort out your India-side finances, build adequate liquidity, understand the rules of the country you are moving to and make long-term financial decisions before you leave India.
For someone moving abroad, becoming an NRI is not just an immigration event. It is a financial transition and the preparation should begin before the flight.
Disclaimer: This article is for general informational purposes only. Immigration laws and government policies are subject to frequent change without notice. While we strive to provide accurate updates, readers are strongly advised to verify the latest requirements with the official embassy, consulate, or government portal of the respective country.