



For Indian investors eyeing a US green card through the EB-5 programme, raising $800,000 is often the easier half of the problem. The harder part is proving exactly where that money came from, and every stop it made along the way.
First, the basics. EB-5 is a US visa route for investors, where foreign nationals can apply for permanent residence by putting money into an American business and creating a set number of jobs. The minimum investment is $800,000 for projects that qualify for the lower rate. But having $800,000 sitting in a bank account does not, by itself, explain how the money was earned or accumulated. And that is precisely what US authorities want to see.
To understand what that involves, Financial Express Digital spoke to immigration expert Mithi Jaiswal about how Indian applicants can document the source and path of their EB-5 funds, particularly when the money comes from property sales, business income, family gifts, inheritance, loans or a combination of sources.
Where can EB-5’s $800,000 investment come from?
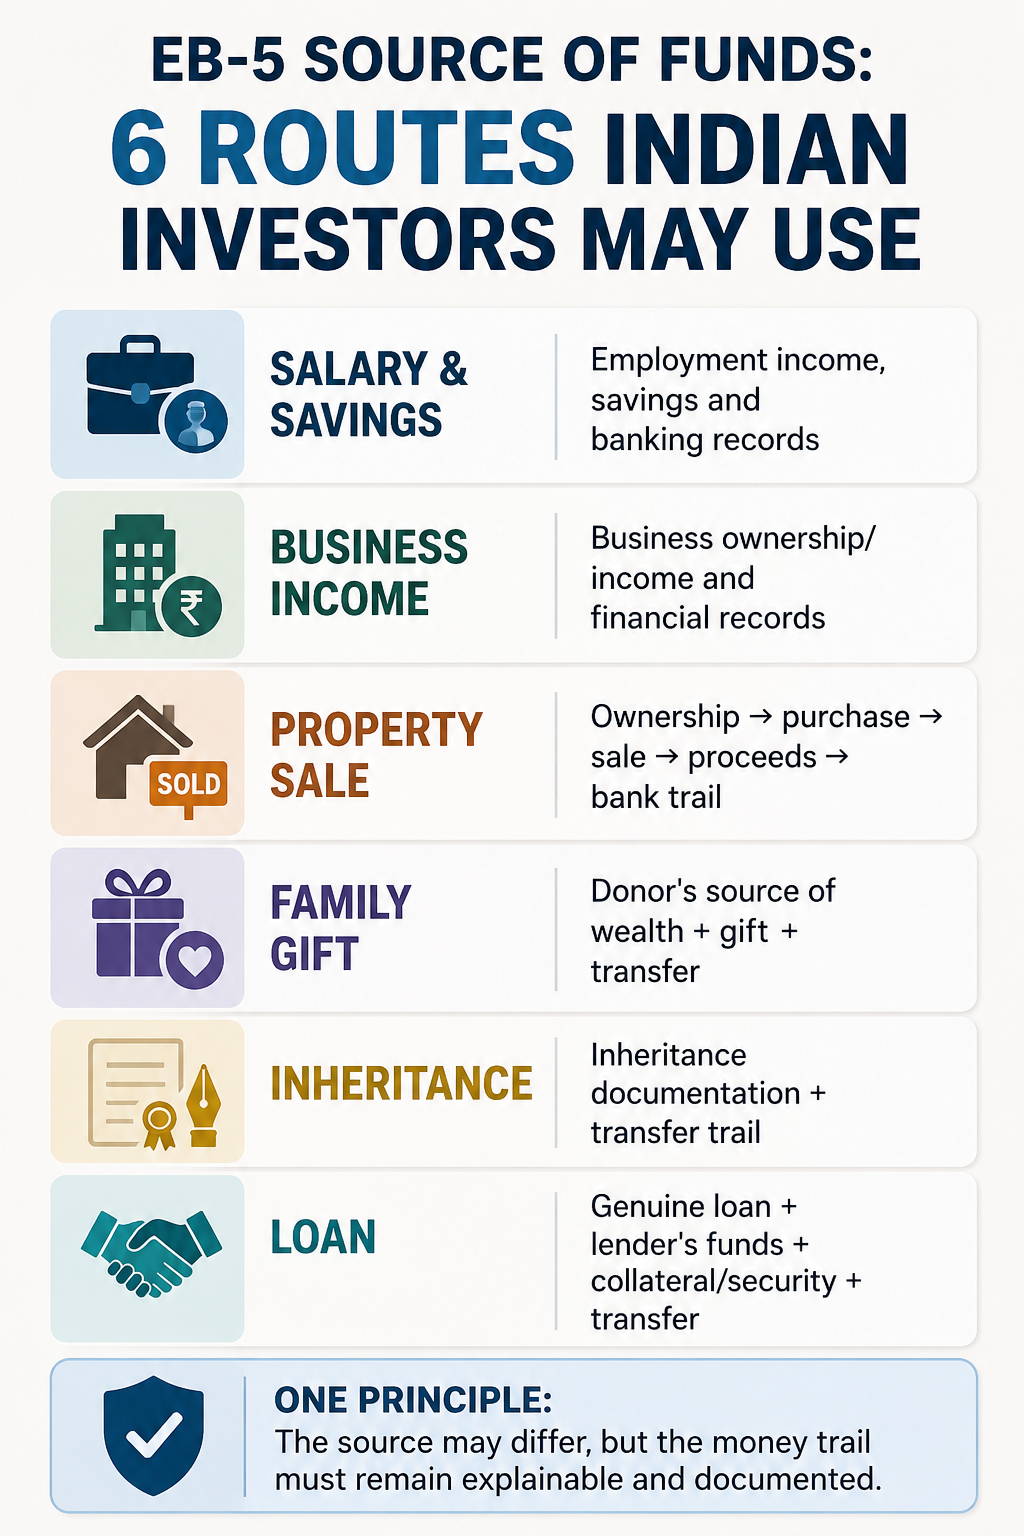
Indian EB-5 applicants do not necessarily rely on a single source of funds. Jaiswal says she commonly sees investors use accumulated salary and savings, business income, proceeds from property or other investments, family gifts, inheritance and loans secured against assets.
“The important thing is that there is no requirement that the $800,000 necessarily originate from one particular type of asset,” Jaiswal says. The key issue is whether the investor can establish a clear, credible and documented trail showing how the money was lawfully earned, accumulated, transferred and ultimately invested.
For example, an investor could have accumulated savings through employment, invested some of that money, sold a property and then transferred the proceeds through one or more bank accounts before sending the funds to the US.
In such a case, the documentation cannot necessarily start with the final transfer.
What is biggest EB-5 source-of-funds red flag?
The problem is not necessarily that the money came from an impermissible source. It can be that there is a gap in the explanation of how the money moved. Jaiswal describes the biggest red flag as an “unexplained financial jump” — money appearing in an account without a documentary trail establishing where it came from.
According to Jaiswal, other common problems include:
- Gaps in bank statements
- Transfers between multiple accounts without an explanation
- Figures that do not match across tax returns and financial records
- Undocumented cash transactions
- Income or assets that cannot be reconciled with reported earnings
A bank statement showing that an investor eventually has $800,000 available does not necessarily explain how that amount was accumulated.
Why EB-5 source-of-funds trail may go back years
Property can be an important source of wealth for Indian families and proceeds from a real estate sale can potentially be used for an EB-5 investment, Jaiswal says.
But documenting the sale alone may not be enough.
Depending on the circumstances, an investor may need to establish:
- Proof of ownership
- Purchase documents and property records
- Original purchase price
- Sale deed and eventual sale price
- Bank statements showing receipt of the proceeds
- Tax records and capital-gains documentation
- Evidence of the buyer’s payment
According to Jaiswal, the exercise can become more complicated when the property was acquired many years ago, inherited, jointly owned or gifted within the family.
There may also be differences between transaction documents and banking records. For example, the sale agreement could show one amount while the bank account reflects payments made on different dates or in different amounts.
Jaiswal recommends reconstructing the transaction chronologically rather than simply collecting the sale deed and latest bank statement. The objective is to allow an adjudicator to follow the money from the original acquisition of the property, through its sale and subsequent transfers, until it reaches the EB-5 investment.
Can family gifts be used for EB-5? Donor’s source of funds matters
A family gift can also form part of an EB-5 investment, but the source-of-funds inquiry does not necessarily end when the money reaches the investor. Instead, the question can move one step backward. “One of the most common mistakes is documenting the transfer from the donor to the applicant but not documenting how the donor accumulated the gifted funds in the first place,” Jaiswal says.
A gift package would generally need to establish the relationship between the donor and investor, the transfer itself and the donor’s ability to provide the funds.
Depending on the circumstances, this could involve bank statements, tax returns, salary records, business documents, property-sale records, investment statements or inheritance documents.
For an investor receiving a large family gift, therefore, the source-of-funds trail may need to cover both the donor’s wealth and the subsequent transfer to the applicant, Jaiswal explains.
What if $800,000 comes from a loan?
Loan proceeds can potentially be used as EB-5 capital, but the arrangement needs to be properly documented.
Jaiswal says investors using loan proceeds should be prepared to establish that the loan is genuine, supported by a clear loan agreement or promissory note, and that the lender actually had the funds available.
The transfer of the loan proceeds also needs to be traceable.
For secured loans, documentation relating to the collateral and the investor’s ownership interest in that collateral can also become important.
The source of the loan proceeds and the security for the loan are separate parts of the documentation, she explains.
Problems can arise when there is no formal loan documentation, the lender’s source of funds is unclear or the loan proceeds cannot be traced to the EB-5 investment.
According to Jaiswal, a loan should not appear as simply another unexplained entry in a bank statement. It needs to fit into the broader source-and-path-of-funds story.
Why Indian EB-5 investors face another layer: LRS, FEMA and RBI rules
For Indian applicants, the money trail does not necessarily end with US immigration documentation. Foreign-exchange compliance can add another layer, particularly when large transfers take place over multiple financial years or involve different family members.
Jaiswal speaks about India’s Liberalised Remittance Scheme (LRS) and the applicable FEMA and RBI framework. For a resident individual, the LRS currently permits remittances of up to $250,000 per financial year for permitted transactions, subject to applicable rules.
Since an EB-5 investment can be substantially larger than that annual threshold, the timing and structure of transfers become important.
From the immigration perspective, the US record should be consistent with the Indian banking and foreign-exchange records. Depending on the circumstances, investors may therefore need to retain documents such as remittance applications, Form A2, bank records, foreign-exchange conversion records and wire confirmations.
Jaiswal recommends addressing this issue before transferring the money, rather than trying to reconstruct the process later.
Investors should also obtain appropriate Indian tax and foreign-exchange advice because satisfying US immigration requirements does not automatically establish compliance with Indian laws governing remittances, she adds.
What should EB-5 investors do before moving $800,000?
For someone considering EB-5, Jaiswal advises, “Map the money before moving the money.”
Before making the investment, she recommends preparing a chronological source-and-path-of-funds map that begins with the original source of wealth and ends with the EB-5 investment account.
Every significant movement should have an explanation and corresponding documentation.
That exercise can expose missing historical bank statements, unexplained deposits, undocumented family transfers or inconsistencies in tax records before the application is filed.
Jaiswal says these problems are generally easier to address before the investment is made and the petition prepared than after USCIS raises questions.
For Indian investors, preparing the source-of-funds package should therefore be viewed as a financial reconstruction exercise, not merely a document-collection exercise.
An adjudicator who knows nothing about the investor’s finances should be able to follow the money from its lawful origin all the way to the $800,000 EB-5 investment without having to fill in the gaps themselves.
Disclaimer: This article is for general informational purposes only. Immigration laws and government policies are subject to frequent change without notice. While we strive to provide accurate updates, readers are strongly advised to verify the latest requirements with the official embassy, consulate, or government portal of the respective country.