



The defence indigenisation in India is entering a better phase. After years of focusing on building major platforms such as artillery systems, helicopters, missiles, fighter aircraft, and warships in the country, the next phase is targeting the raw materials, components, subsystems and spares that go inside them.
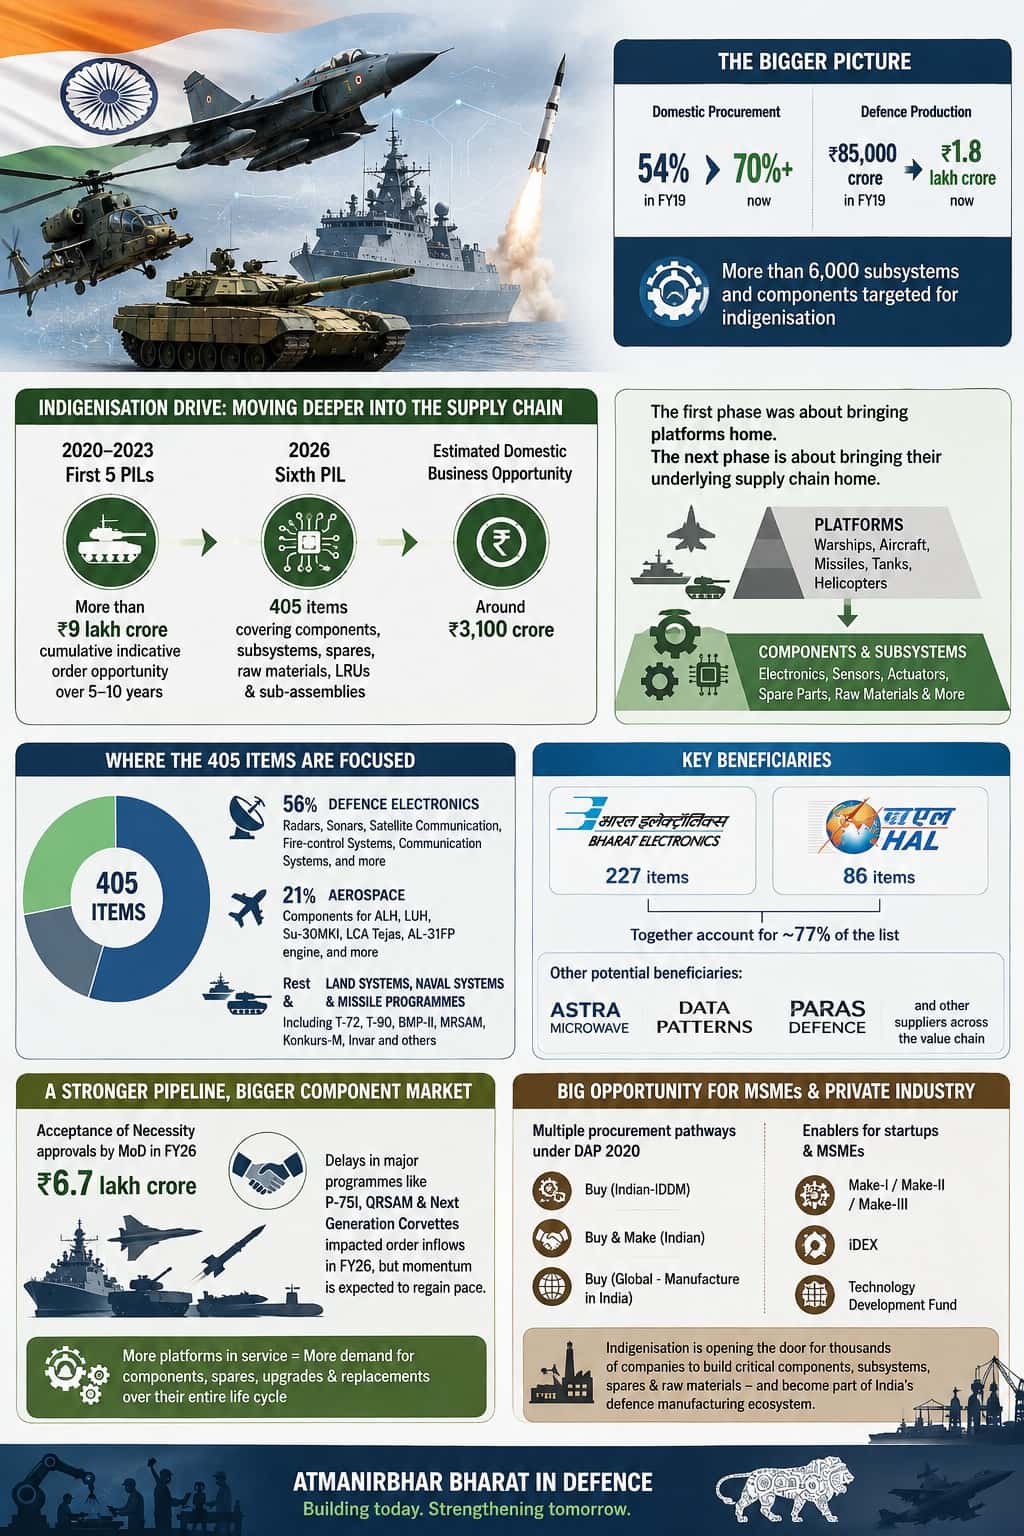
The shift is seen in the sixth Positive Indigenisation List (PIL) notified by the Ministry of Defence. The list covers 405 items and represents an estimated domestic business opportunity of around Rs 3,100 crore, according to Kotak Institutional Equities. Unlike the earlier lists, the latest list is dominated by critical line-replaceable units (LRUs), sub-systems, sub-assemblies, spares, components and raw materials.
Therefore, the highlight of the latest list lies not merely in the Rs 3,100 crore opportunity. It points to a bigger change in India’s defence manufacturing strategy where it shows indigenization is moving deeper into the supply chain.
From platforms to the components inside them
According to Kotak’s Aerospace & Defense report, the defence procurement ecosystem in India has changed since the introduction of the Defence Acquisition Procedure (DAP) 2020. The domestic procurement has risen from 54% of total defence procurement in FY19 to more than 70%, while defence production has increased from Rs 85,000 crore to around Rs 1.8 lakh crore over the same period.
More than 6,000 subsystems and components are also targeted for indigenisation. That potentially expands the opportunity well beyond companies that manufacture complete aircraft, ships, missiles or armoured vehicles.
A fighter aircraft may be a single platform from a procurement perspective, but its manufacture and operation depend on thousands of individual components from avionics, sensors and communication equipment to actuators, electronic systems, spares and specialised materials. India’s latest policy push is aimed at capturing more of that value domestically.
The Rs 9 lakh crore opportunity came first
The scale of the indigenisation drive becomes clearer when the sixth PIL is viewed alongside the first five lists. The brokerage firm estimates that five PIL announced between 2020 and 2023 represented more than Rs 9 lakh crore of cumulative indicative order opportunity over the subsequent five to 10 years. However, that figure needs to be understood well. Kotak’s report refers to the potential order opportunity associated with those five lists and is not the value of DAP 2020 itself.
The Rs 3,100 crore opportunity associated with the list is also not directly comparable with the Rs 9 lakh crore estimate as if they are competing figures. Instead, they represent different layers of India’s indigensation drive. The earlier lists created opportunities around major platforms and defence equipment. the sixth list goes further down the chain, targeting the components and subsystems required to build, operate and maintain those platforms.
The first phase was about bringing platforms home and the next phase is about bringing their underlying supply chain home.
Defence electronics emerges as the biggest opportunity
The composition of the sixth list is particularly significant for India’s defence electronics industry. Around 56% of the 405 items are linked to defence electronics, according to the brokerage firm. These include equipment and components associated with radars, sonars, satellite communication systems, fore-control systems and communication systems, among other mission-critical technologies. Bharat Electronics Ltd (BEL) has a particularly large presence.
Of the 405 items, 227 are linked to BEL, while 86 are linked to Hindustan Aeronautics Ltd (HAL). Together, the two defence public-sector companies account for around 77% of the items on the list, the firm said. But the opportunity could extend well beyond the two large PSUs.
The brokerage firm identifies companies including Astra Microwave, Data Patterns and Paras Defence as potential beneficiaries of the broader electronics opportunity. The reason is that localising a subsystem can potentially create work for several suppliers across the value chain rather than concentrating the entire opportunity with one prime contractor.
Aerospace accounts for another major share
Aerospace represents around 21% of the sixth-list items, according to Kotak. The list includes components associated with the Advanced Light Helicopter (ALH), Light Utility Helicopter (LUH), Su-30MKI and LCA Tejas, as well as the AL-31FP engine. The indigenisation effort also extends to other military systems, including missile programmes such as MRSAM, Konkurs-M and Invar, land platforms including the T-72, T-90 and BMP-II, and naval systems.
The aerospace component is particularly important as it extends localisation beyond India’s newest indigenous platforms. The Su-30MKI-related requirements’ inclusion, for instance, shows that the policy can also create opportunities around aircraft already in service, not just newly developed systems. That means domestic companies can potentially benefit from both new-platform production and the long-term requirement for components and spares.
More platforms could mean a larger component market
The deeper localisation push is also arriving as India prepares for a substantial defence procurement cycle. According to Antique Stock Broking, the brokerage firm estimated that the Ministry of Defence granted Acceptance of Necessity approvals worth Rs 6.7 lakh crore in FY26.
The brokerage has also highlighted delays in major programmes such as the P-75I submarine programme, QRSAM and Next Generation Corvettes, which contributed to a decline in order inflows for listed defence public-sector companies during FY26. However, Antique expects ordering momentum to regain pace.
For India’s component manufacturers, the significance is straightforward: every new aircraft, helicopter, missile, warship or armoured vehicle creates a corresponding ecosystem of components, replacement parts and support requirements. The larger the installed defence fleet becomes, the larger that potential supply chain can become.
Why this could be a bigger opportunity for MSMEs
The move towards components and subsystems could also alter the structure of India’s private defence industry. DAP 2020 created multiple procurement routes with different indigenous-content requirements rather than simply instructing the armed forces to “buy Indian”.
The framework includes categories such as Buy (Indian-IDDM), Buy & Make (Indian) and Buy (Global – Manufacture in India), creating different pathways for domestic companies and foreign OEMs to participate in local manufacturing.
At the same time, initiatives such as Make-I, Make-II, Make-III, iDEX and the Technology Development Fund have created routes for startups and MSMEs to develop and manufacture defence technologies. That becomes increasingly relevant as indigenisation moves towards smaller components.
A company does not need to build an entire fighter aircraft to participate in the Tejas ecosystem. It could instead manufacture a specialised electronic component, avionics unit, subsystem, spare or material used by the aircraft.
(This article highlights specific listed defence electronics companies (BEL, BDL, Astra Microwave, Data Patterns, and Paras Defence), referencing third-party market projections, itemised procurement lists, and financial estimates from Kotak Institutional Equities and Antique Stock Broking. While it provides insight into India’s defence indigenisation policies, these forward-looking estimates depend on government procurement approvals and tender execution. This content is for informational purposes only and does not constitute investment advice or a solicitation to buy or sell securities. Readers are strongly advised to evaluate their risk appetite and consult a SEBI-registered investment advisor before making financial decisions based on these projections.)