


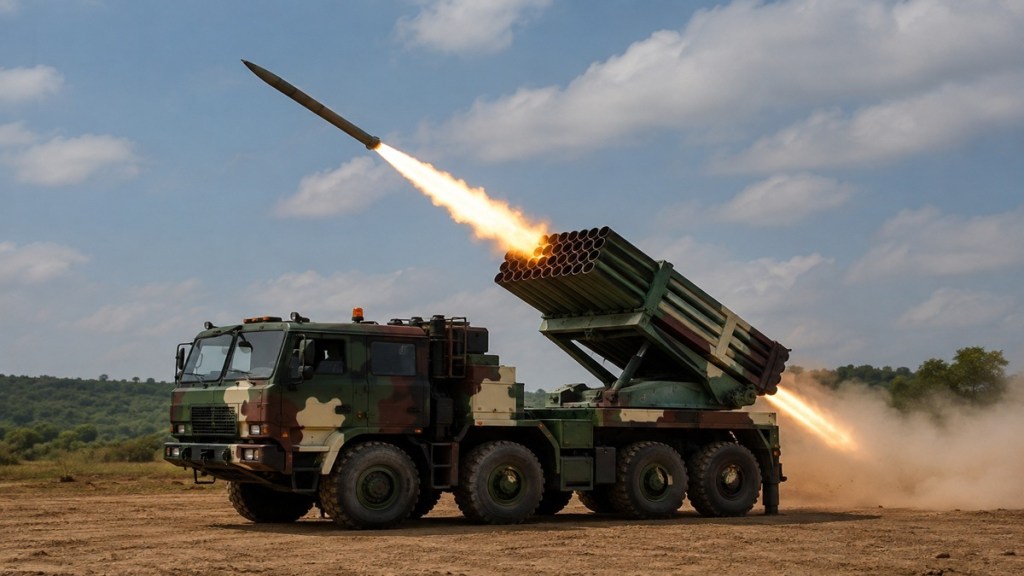

Pinaka has emerged as one of India’s most significant indigenous multi-barrel rocket launcher systems, combining high battlefield impact, rapid salvo-fire capability and an expanding domestic manufacturing base.
For Solar Industries India Ltd, the programme is becoming a key long-term growth driver. The company is the only private-sector player to hold transfer-of-technology rights for Pinaka rockets, putting it in a position to benefit from sustained production and upgrade orders.
Its revenue from the Pinaka programme is estimated to exceed Rs 60 billion between 2026 and 2030, supported by execution of Mk-1 and ADM orders, potential Mk-2 contracts, and longer-term opportunities from the proposed Mk-3 and Mk-4 variants, according to Kotak Institutional Equities report.
At the operational level, Pinaka is a high-performance indirect fire artillery rocket system developed by the Defence Research and Development Organisation (DRDO), ARDE and High Energy Materials Research Laboratory (HEMRL) in Maharashtra‘s Pune.
Each launcher carries two pods with six rockets each, enabling quick single-shot or salvo deployment, while the system’s solid propellant propulsion, wrap-around fin stabilizers, monolithic warhead and precision fuze mechanism give it strong battlefield utility.
The platform has four variants in use today and it remains combat-proven, with a decisive role in the 1999 Kargil War where it was used against entrenched high-altitude targets.
- Pinaka Mk1
- Mk1 Enhanced
- Mk2
- ADM
Firepower evolution of Pinaka
The Pinaka family is evolving in a layered way. Mk1 is the original unguided system with a range of 38-40 km, no guidance, and a Circular Error Probable (CEP) of about 500 metres. Mk1 Enhanced raises the range to 45-60 km and improves accuracy to around 250 metres, while retaining the same salvo profile and reload cycle.
Guided Pinaka Mk II takes the next step, with a 65-75 km range and GPS-based guidance that brings CEP down to roughly 50 metres. The ADM variant serves a different battlefield purpose, using cluster munition effects for area denial rather than precision strikes. Together, these versions allow the Indian Army to bridge the gap between mass firepower and precision deep-strike capability.
The operational advantages are substantial. Pinaka can reportedly fly at around Mach 4.7, or about 5,800 km per hour, making interception difficult. It also supports a classic shoot-and-scoot doctrine as 12 rockets can be launched in less than a minute, after which the launcher can quickly reposition to reduce vulnerability to counter-battery fire. This combination of speed, saturation fire and mobility is a major reason for the system’s enduring relevance.
Pinaka’s industrial ecosystem
Pinaka is also a strong example of India’s defence public-private partnership model. The system has seven major components — ammunition, launcher, fire control system, command post vehicles, mobility platform, electronics and navigation — and a large share of these are now built by Indian private sector players.
Solar supplies the rockets, Tata Advanced Systems contributes launchers, fire control systems and command post vehicles, Larsen & Toubro (L&T) is involved in launcher and command vehicle production, BEML handles the truck platform and electronic stabilisation, and BEL contributes to electronics. Ammunition and launcher components account for the largest share of the system’s cost, which means Solar is a top-tier beneficiary of the programme’s expansion.
Solar Industries’ position is especially strong because of its unique transfer-of-technology (ToT) status. In October 2022, Defence Research and Development Organisation (DRDO) flight-tested Pinaka Mk1 Enhanced and ADM at Pokhran and transferred technology to only two entities — Munitions India and Solar via Economic Explosives — making Solar the only private company with Pinaka EPRS/ADM manufacturing capability.
In February 2025, the Ministry of Defence (MoD) placed a Rs 102 billion order for high-explosive ammunition and ADM, with Solar securing 60 per cent of the value, or about Rs 61 billion, while Munitions India received the remaining 40 per cent. Commercial supply began in 4Q2026.
The revenue trajectory is equally compelling. Solar’s Pinaka revenue is expected to cross Rs 60 billion over 2026-30E, supported first by existing domestic orders for Mk1 and ADM, then by Mk2 execution, and later by exports and new orders. For Mk1 and ADM, the company’s domestic orderbook stood at Rs 60,840 million in 2025 and is expected to execute steadily over a decade, with annual revenue stabilizing at around Rs 6,084 million from 2026 onward.
The Mk2 domestic programme adds another major leg, with an estimated Rs 68,040 million order inflow and annual revenue of roughly Rs 6,804 million once execution normalizes.
Exports are becoming increasingly important. Solar has already shipped guided Pinaka rockets to Armenia, and the company sees further demand from Southeast Asia and Europe, including France. The export orderbook is expected to grow with repeat orders, and analysts are baking in about Rs 10 billion a year from exports over 2026-2030E. That makes the Pinaka line not just a domestic defence story, but a growing international business as well.
Long-term optionality and strategic significance
The bigger opportunity may come later. The Indian Army is expected to field more Pinaka regiments over time, and Mk2/Guided Pinaka could generate a large fresh demand cycle. For 10 regiments of Mk2/Guided Pinaka, one estimate places requirement at about 20,000 rockets, translating into roughly Rs 136 billion of revenue opportunity at an average selling price of around Rs 7 million per rocket.
If Solar captures 50 per cent of that, it could generate about Rs 70 billion over 2027-2036E, with deliveries likely staggered across a long induction cycle similar to Mk1.
Solar’s defence orderbook further reinforces this outlook. Over 2024-2026, the company received defence order inflows of about Rs 170 billion, and its orderbook stood near Rs 180 billion as of March 2026. Roughly Rs 60 billion of that is tied to the long-cycle Pinaka programme, while around Rs 120 billion comes from high-explosive ammunition and other orders executable over 3-4 years. A significant share of the non-Pinaka book is export-oriented, spanning the Americas, Europe and Asia.
In short, Pinaka is no longer just an indigenous rocket system; it is a platform around which India is building a broader artillery ecosystem, export opportunity and private-sector defence manufacturing base. For Solar, the combination of exclusive ToT access, early production wins, export traction and future Mk2/Mk3 options makes Pinaka one of the company’s most strategically important programmes.