



At a recent event, Uday Shankar, vice-chairman of JioStar, noted that while sports has been a strong investment for the broadcaster, it remains financially challenging while the media industry is under pressure as advertising models come under strain globally.
JioStar holds the media rights for the most valuable cricket league, the Indian Premier League (IPL), whose business value has skyrocketed to $20 billion (around Rs 1.97 lakh crore, according to Houlihan Lokey’s 2026 IPL Brand Valuation Study) after its 19th season this year.
IPL’s media rights for the IPL were sold to Viacom18 and Disney Star back in 2022 for a five-year period for over $6 billion (or Rs 48,300 crore approximately), prior to the merger of the two broadcasters. Disney Star bagged the ICC media rights deal for the 2024-27 period for $3.2 billion (around Rs 25,000 crore).
In comparison, Disney Star’s eight-year ICC deal for 2015-23 was about $2 billion. Cricket continues to dominate the sports ecosystem, accounting for an estimated 85% of media and sponsorship revenues.
Industry estimates indicate that while the cost of cricket media rights saw a threefold increase in recent cycles, advertising revenues are growing moderately by around 15-20% annually. Santosh N, managing partner, D and P Advisory, says the current situation is the “classic winner’s curse territory”. The buyer who wins the auction often overpays relative to the revenue the rights can generate on a standalone basis.
Linear TV advertising growth has slowed, and converting free digital scale into sustainable subscriptions remains difficult in a price-sensitive market, say experts. “The smarter players do not treat cricket as a pure content P&L. They treat it as a strategic asset that drives subscriber acquisitions and commands premium ad rates,” says Santosh. Such tentpole properties do make the platform more valuable. Companies are therefore willing to accept even “negative direct returns” on the rights investments.
Hybrid play
Despite the skyrocketing cost of cricket media rights, there will likely be a value rationalisation in the near future for some media rights, says Ashish Pherwani, partner & leader, media & entertainment sector, EY India. “Monetisation models are changing, incorporating e-commerce, product or service trials, registrations and other market-facing actions,” he observes. While these are nascent, they will need to scale up to keep monetisation in sync with current advertiser requirements.
The key to offset staggering rights fees is to deploy a hybrid monetisation playbook, says Navin Khemka, president, client solutions, WPP Media South Asia. This includes programmatic TV and interactive commerce, which involves the integration of shoppable ads during live streams.
Compared to the cultural monopoly of cricket, Khemka points out that alternative sports represent highly targeted and cost-effective alternatives for media platforms.
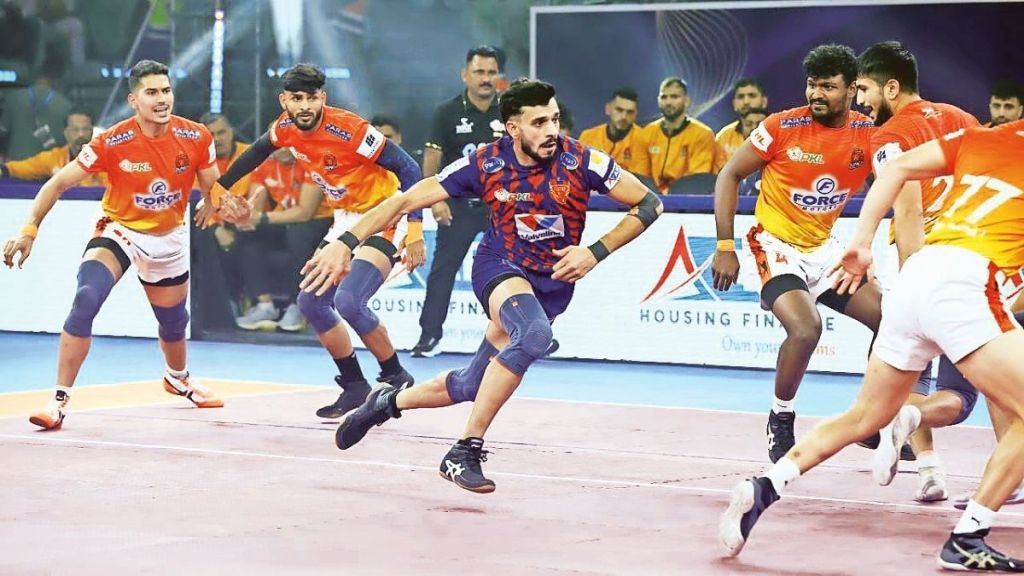
“Alternative sports could capture heavy viewership if they are repackaged for modern television,” he says. Kabaddi is a good example of emerging sports making a new niche for itself. “By taking a sport that is indigenous and unorganised, and by applying world-class camera work, analytics, and prime-time scheduling, the Pro Kabaddi League is now the second-most-viewed spectator sport in India,” he adds.
Networks like Zee are pursuing football in a big way, picking up the media rights for FIFA tournaments, as well as the German and Italian football leagues. Observers note that sports such as football draw highly passionate, Gen Z and urban audiences willing to pay for premium content.
Experts say sports will continue to reshape the country’s media ecosystem and the winners will be those that can solve the monetisation and cost-structure challenges. Cricket will remain the instrument for scale, while other sports provide diversification, growth and margins.