



Prime Minister Narendra Modi has set a new benchmark for Indian banking: at least one Indian lender among the world’s top five. “The banking sector in India is flourishing; one Indian bank should be among the top five globally,” Modi said in his Independence Day speech on Saturday.
So where do Indian banks currently stand on the global league tables — and what would it take to close the distance? The numbers tell a story of a sector that has grown rapidly at home but remains, by global standards, a middleweight punching in a heavyweight division. The gap, in short, is formidable.
A ranking by S&P Global Market Intelligence, which measures banks by total assets, shows the scale of the challenge more starkly. The summit is dominated by China’s state-owned giants — ICBC leads with a $7.65-trillion balance sheet, followed by Agricultural Bank of China at $6.97 trillion and China Construction Bank at $6.52 trillion — while JPMorgan Chase holds fifth place with $4.42 trillion.
India’s champions are some distance down the slope. SBI, the country’s largest bank, ranks 45th with assets of $877 billion, while HDFC Bank is 76th at $515 billion. To match the world’s fifth-largest bank, SBI’s balance sheet would need to swell roughly fivefold.
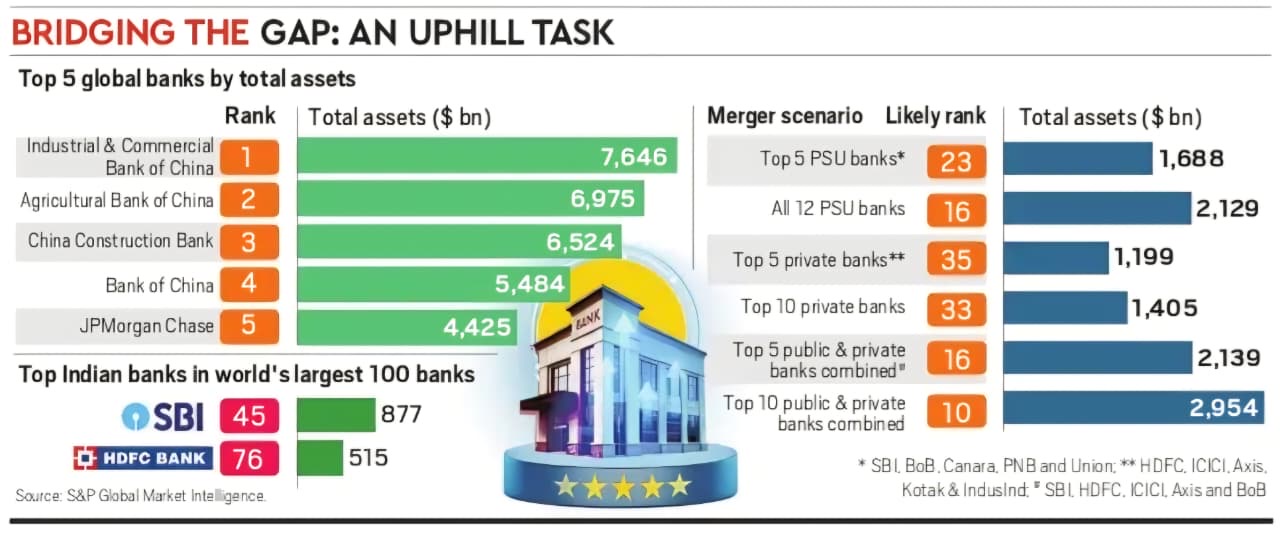
Consider this: even if all 12 of India’s public sector banks were merged into a single colossus, their combined assets of roughly $2.13 trillion would still leave it ranked 16th globally. Only a merger of the top 10 public and private sector banks would propel the combined entity into the global top 10.
None of this makes the target a pipe dream, industry experts say — but it does make it a marathon rather than a sprint. “Bridging this gap would require India’s largest banks to approximately double or triple their balance sheets over the next two decades, which is ambitious but achievable,” said Pratik Shah, national financial services leader at EY India.
Shah’s road map for getting there runs through four areas: expanding balance sheets through greater capital mobilisation, developing the corporate bond market, deepening participation in international trade and cross-border financial flows, and leveraging artificial intelligence to improve productivity, risk management and customer experience.
Consolidation could shave years off the journey, said Neha Gupta, managing director and partner at BCG — and India has already seen a preview of what a well-timed merger can do to the rankings. “Closer home, we saw that in the case of HDFC Bank, which jumped more than 25 ranks to enter the top 100 banks after its merger with HDFC Ltd,” Gupta said.
But bulking up comes with its own baggage. Gupta noted that the Indian regulator has already identified systemically important banks, and cautioned that squeezing a roughly $900-billion banking industry into two or three large lenders could leave the sector excessively concentrated. “So what we need is a few large global-scale banks, but also a set of smaller banks to serve the long tail,” she added.