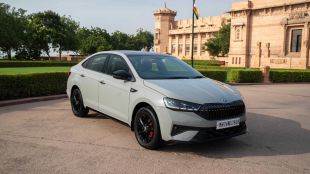
The passenger vehicle market staged a sharp recovery in the first half of FY27, with sales at the country’s four largest carmakers rising 30.2% year-on-year to 2.1 million units in April-September 2026, as lower taxes, improved affordability, strong SUV demand and new model launches lifted purchases. The figures, which cover Maruti Suzuki, Tata Motors, Mahindra & Mahindra and Hyundai Motor India, point to a broad-based revival in the market after a relatively subdued period.
The performance also reflects the impact of the GST rate reduction on passenger vehicles announced in September 2025. The lower tax burden improved vehicle affordability and provided a demand boost, with the benefit becoming more visible in the first half of FY27. However, the year-on-year comparison will become progressively less favourable in the second half as the GST-led increase in volumes gets incorporated into the base.
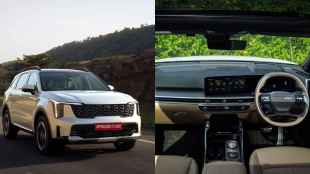
A key feature of the recovery has been the continuing shift in consumer preference towards SUVs. Maruti’s volumes increased 56% during the period, while Mahindra’s growth continued to be led by its SUV portfolio. Tata Motors also recorded strong growth in its passenger vehicle business, with its electric vehicle portfolio providing an additional growth lever.
The changing product mix is also becoming increasingly important to the market. Automakers are expanding their portfolios across electric, CNG and conventional powertrains, giving consumers more options while responding to tightening emission requirements and changing demand patterns.
At Maruti, the recovery was broader across segments, with hatchback volumes rising 41% in H1, alongside the stronger growth in SUVs. The company is also expanding its CNG and electric vehicle offerings, indicating that the recovery is not confined to a single powertrain or vehicle category.
The industry is now entering the crucial second half of the financial year, when the comparison base will be higher and the initial benefit of the GST reduction will be fully reflected in year-ago numbers. Analysts expect the percentage growth rate to moderate, even as absolute volumes rise, with festive demand and a sizeable pipeline of new models providing support.
According to analysts, the key test for the industry in H2 will therefore be whether consumer demand can sustain the momentum seen in H1 without the same degree of support from the GST-led affordability boost. A moderation in growth would not necessarily indicate a reversal, but would provide a clearer measure of the underlying health of the passenger vehicle market, analysts added.