Allied Blenders & Distillers

Related News
Disney’s new tech boss is an IIIT Hyderabad Grad: Meet Karandeep Anand, company’s first-ever CTO
‘We expect our rental income to top Rs 4,000 crore by FY30’: Prestige Estates Projects’ Irfan Razack
IT sector Q2FY27: Infosys, HCL Tech, Wipro, Tech Mahindra results, interim dividend dates
Man invests Rs 5 lakh in Bitcoin, sees it grow 140 times; faces tax scrutiny, ITAT says this
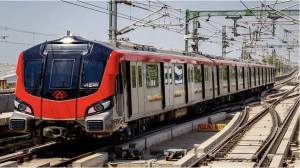
Lucknow Metro Phase 1B: 12 new stations to bring metro closer to Aminabad, Chowk and KGMU